

What if the infrastructure of your commercial building was actually a dormant financial asset waiting to be unlocked? Whilst most business owners rely on general accounting to manage tax liabilities, many unknowingly leave thousands of pounds on the table. Standard filings often miss the 'embedded' items hidden deep within a property's fabric. Identifying capital allowances on property requires a specialist forensic approach to distinguish between a building's permanent structure and the integral fixtures that qualify for significant relief.
It's common to feel that traditional accounting might overlook these intricate details, especially when the line between a 'fixture' and a 'structure' seems blurred. This guide provides a clear roadmap to identify hidden savings, helping you improve cash flow and maintain HMRC compliance with total confidence. We'll explore the 2026 tax landscape, including the new 40% First-Year Allowance and the 14% main pool Writing Down Allowance. You'll learn how to transform your property into a strategic business tool through precise, expert recovery.
Key Takeaways
- Discover how to unlock significant tax relief by identifying capital allowances on property that are often missed during standard accounting procedures.
- Understand the distinction between a building's structure and its qualifying fixtures to ensure you don't leave unclaimed capital within your purchase price.
- Master the 2026 tax landscape, including the £1 million Annual Investment Allowance and the newly introduced 40% First-Year Allowance for qualifying expenditure.
- See why a specialist forensic survey is the most effective way to document every qualifying asset and maximise your recovery while remaining fully HMRC compliant.
- Explore a success-based approach to financial recovery that transforms complex regulatory procedures into a low-risk opportunity for business innovation.
What are Capital Allowances on Property and Why Do They Matter?
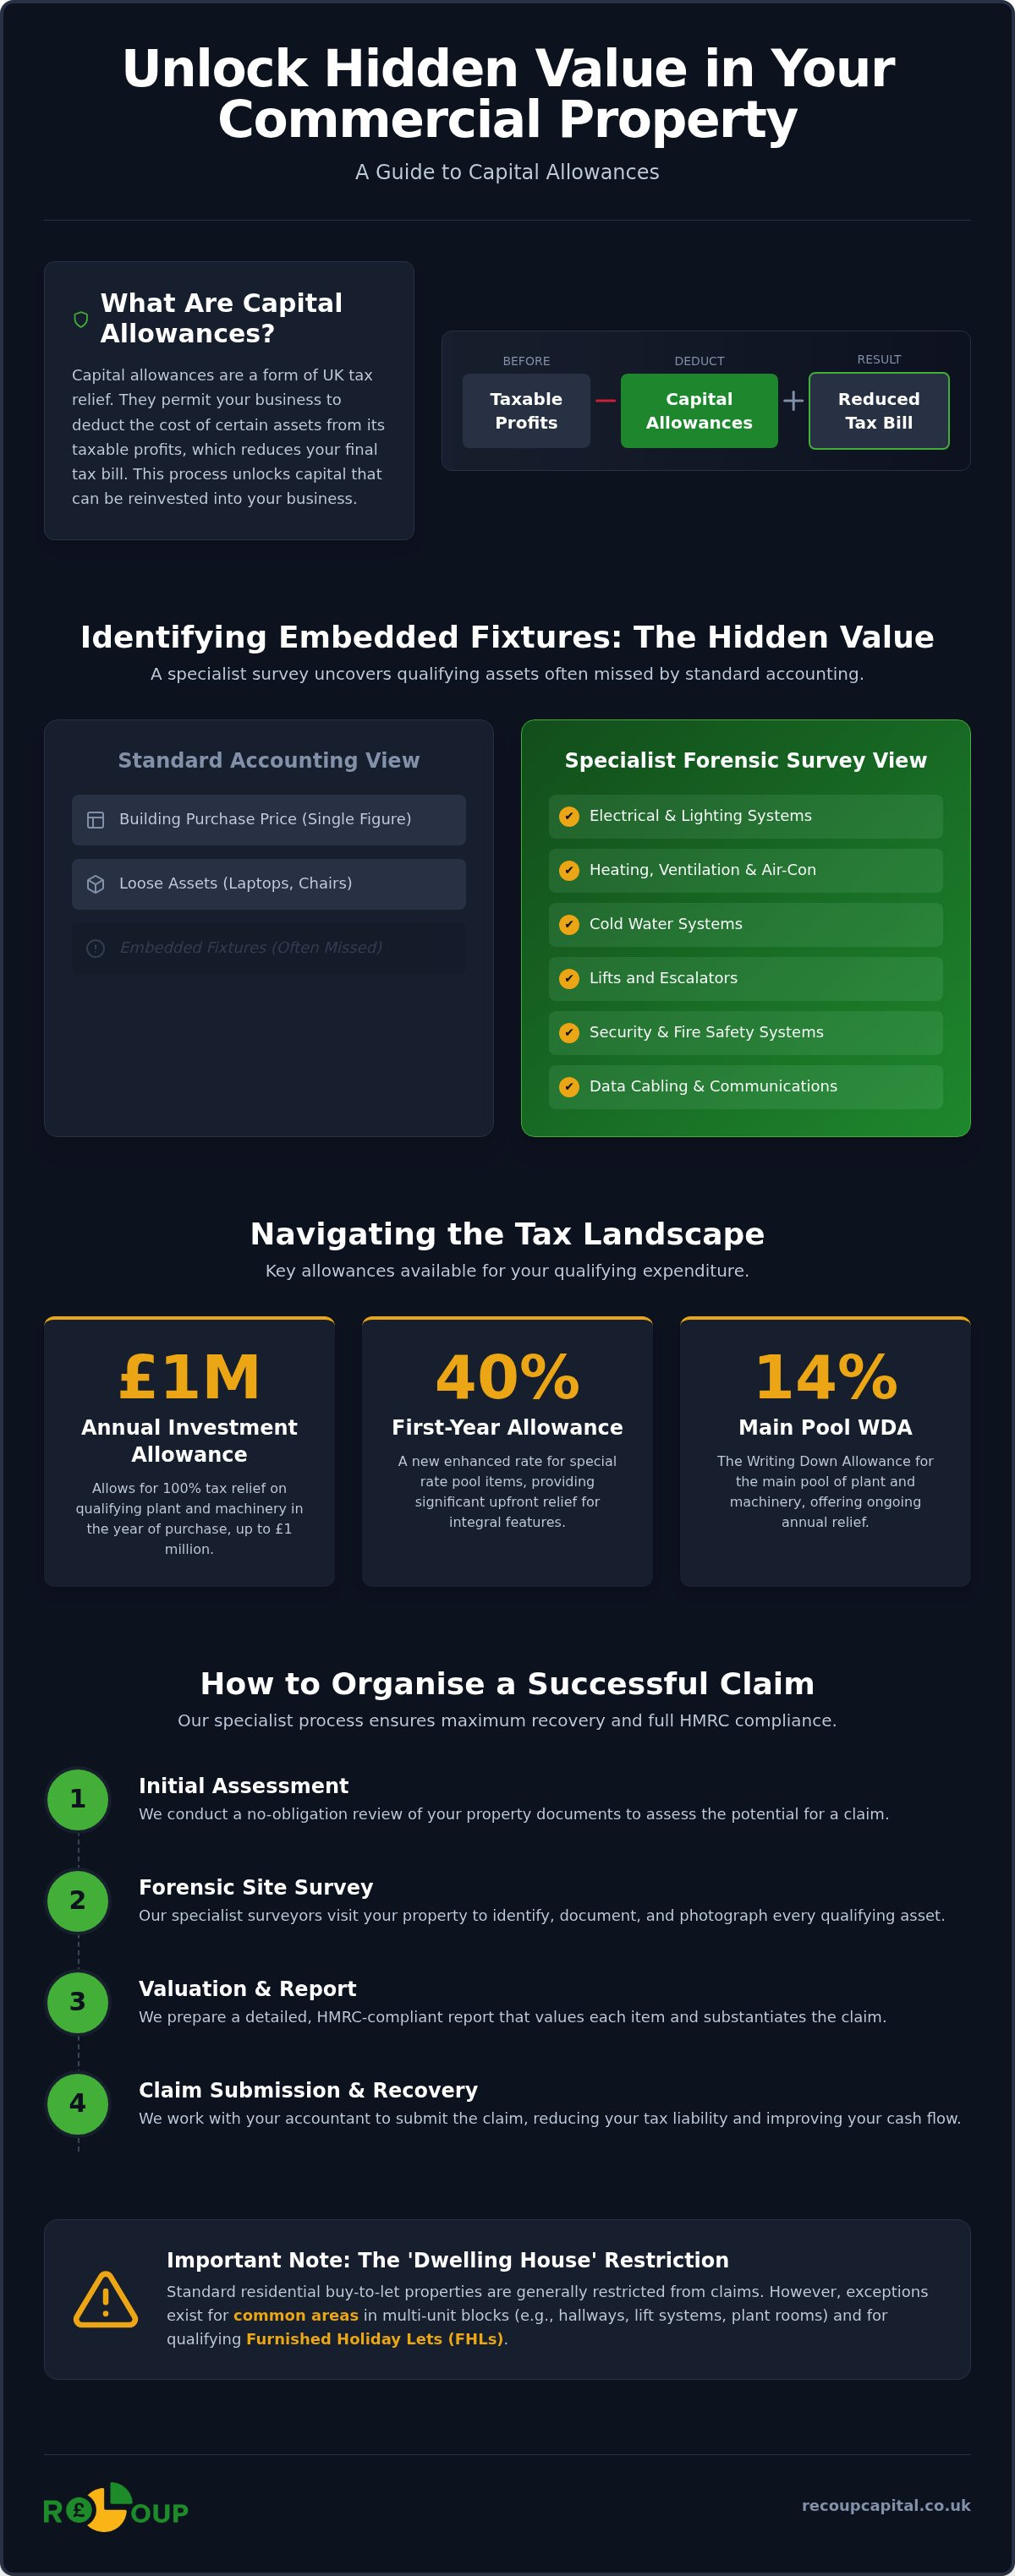
Are you maximising the value of your commercial investment? To understand the full potential of your building, you must first define the mechanism of recovery. What are Capital Allowances? In short, they are a statutory form of UK tax relief. They allow your business to deduct the cost of certain capital assets from its taxable profits, effectively reducing the amount of tax you owe. Whilst the concept is straightforward, applying capital allowances on property is a specialised task that goes far beyond standard bookkeeping.
Property is a unique asset class because it's a composite of different elements. Most accountants easily identify 'loose' assets like laptops or office chairs. However, a significant portion of a building’s value is tied up in 'embedded' fixtures. These include electrical systems, heating, and security installations. These items are often hidden within the purchase price or construction costs. Because they aren't visible on a simple invoice, they frequently go unclaimed by general practitioners.
The financial impact of these claims is substantial. By identifying these systems, you can significantly lower your Corporation Tax or Income Tax liabilities. This isn't just a tax refund; it's a way to reclaim capital to reinvest in your business growth. Because our team operates on a success-based fee model, exploring these hidden savings becomes a no-risk opportunity for your firm to innovate and expand.
Qualifying Activities for Property Tax Relief
Most commercial property owners are eligible to claim. This includes traditional offices, retail units, and industrial warehouses. Property developers also find value here, particularly when managing the interaction between capital claims and Land Remediation Relief. Even Furnished Holiday Lets (FHL) can still access relief, though navigating the post-2025 regime changes requires precise, up-to-date expertise to ensure your portfolio remains compliant and profitable.
The 'Dwelling House' Restriction
There is a clear line between commercial and residential use. Standard residential buy-to-let properties are generally classified as 'dwelling houses' and are restricted from claiming capital allowances on property. However, exceptions do exist. You may be able to claim for common areas in large residential blocks, such as hallways, lift systems, or plant rooms in apartment complexes. Distinguishing between 'dwelling' areas and 'commercial' or 'communal' spaces is vital for a successful, compliant claim that withstands HMRC scrutiny.
Identifying Embedded Fixtures: Where the Hidden Value Lies
When you purchase a commercial building, the final price tag rarely includes a detailed inventory of every nut, bolt, and wire. Under the Capital Allowances Act 2001, 'fixtures' are items that are legally part of the building but qualify as plant and machinery for tax purposes. Because these assets are physically attached to the property, they're often 'hidden' within the total acquisition cost. Most buyers see a single figure for the property, whilst the underlying value of the systems that make the building functional remains obscured from their balance sheets.
Identifying capital allowances on property requires looking past the walls and ceilings. Common examples include lift systems, air conditioning units, and fire alarms. However, high-value claims often stem from more technical installations like security systems, bespoke lighting, and extensive data cabling. According to official government guidance on capital allowances, these items qualify because they perform a specific function for the business rather than simply being part of the building's setting. Without a detailed survey, these assets are often treated as non-deductible structural costs.
Integral Features: The Core of Your Claim
Integral features represent a specific category of fixtures that HMRC treats with particular care. These include electrical systems (including lighting), cold water systems, and space heating or cooling. They're the most commonly missed items because general accountants often view them as part of the structure itself. In reality, they are distinct assets with their own tax rates. Missing these items means leaving significant relief on the table, as they form the backbone of most property-based claims in the commercial sector.
Forensic Surveying vs. Standard Accounting
Standard property invoices are rarely enough. They lack the granularity required to identify every qualifying asset, which is why a specialist surveyor must reconstruct costs using forensic techniques. This process ensures a 'just and reasonable' apportionment of the purchase price, transforming a vague acquisition figure into a detailed, compliant schedule of assets. This method provides the evidence needed to withstand HMRC scrutiny whilst maximising your financial recovery. If you're unsure whether your current filings capture these details, you can explore our specialised approach to capital allowances to see what might have been missed.
Navigating Different Rates: Plant and Machinery vs Structures and Buildings
Understanding the hierarchy of relief is essential for any savvy property owner. Not all expenditure on capital allowances on property is treated the same. HMRC separates costs into distinct pools, each offering varying speeds of capital recovery. At the top of the pyramid is the Annual Investment Allowance (AIA), which remains a robust tool in 2026. It allows businesses to claim 100% tax relief on up to £1 million of qualifying expenditure in a single year. For many small and medium enterprises, this covers the entirety of their qualifying fixtures.
When AIA is exhausted or unavailable, assets move into Writing Down Allowances (WDA). Keep in mind that as of April 2026, the main pool WDA rate has been reduced to 14%. The special rate pool, which includes integral features like air conditioning and electrical systems, remains at 6%. Conversely, the 'shell' of the building qualifies for the Structures and Buildings Allowance (SBA) at a flat 3% per year. This creates a massive disparity in how quickly you see a return on your capital.
Prioritising Your Claims for Cash Flow
You should always aim to categorise items as plant and machinery rather than SBA where the legislation allows. Whilst SBA offers a steady 3% relief, it takes over 33 years to fully recover the cost. By contrast, the new 40% First-Year Allowance (FYA), introduced in January 2026, provides a significant front-loaded deduction for qualifying main rate plant and machinery. This tax injection improves immediate cash flow, allowing you to reinvest in your operations sooner rather than later. This strategic prioritisation is where a specialist survey truly demonstrates its value.
Full Expensing and the 50% Special Rate
Limited companies have access to even more aggressive relief through full expensing. This allows for a 100% first-year deduction on new and unused main rate assets. If you're investing in integral features, such as lift systems or space heating, you might qualify for a 50% first-year allowance. You must distinguish between 'new' and 'second-hand' purchases here. Full expensing is reserved for brand-new assets. For second-hand acquisitions of capital allowances on property, the forensic survey mentioned previously becomes even more critical to ensure you're using the AIA or WDA pools effectively.
How to Organise a Successful Capital Allowances Claim
How do you actually secure these savings? The process of claiming capital allowances on property follows a rigorous, logical progression. It begins with an initial feasibility study. This stage provides a clear estimate of your potential claim size before any heavy lifting begins. Once the opportunity is confirmed, a specialist site survey is conducted. This isn't a standard building survey. It's a forensic exercise to document every qualifying asset within the structure.
Following the survey, we undertake a forensic cost analysis. This stage involves valuing embedded fixtures that don't have individual price tags. We apply professional quantity surveying skills to determine the replacement cost of assets at the time of construction or purchase, ensuring the valuation is 'just and reasonable'. We then prepare a robust technical report. This document serves as the evidence base for your HMRC submission. Finally, we manage the direct liaison with HMRC. This ensures the claim is processed smoothly and any technical queries are handled with expert precision. Because our team operates on a success-based model, this entire process represents a no-risk opportunity for your business.
The Importance of Section 198 Elections
Property transactions introduce a critical legal hurdle. When you buy or sell a commercial building, you must address the fixtures. A Section 198 election is a joint agreement that fixes the value of these items for both parties. It's a vital step. If you miss this window during the sale process, you could permanently lose the right to claim on those assets. We act as a protective guide to ensure these elections are structured correctly from the start.
Gathering the Right Documentation
Success relies on high-quality evidence. You'll need purchase contracts, completion statements, and any existing survey reports. Don't worry if you're dealing with an older property where original invoices are missing. Our forensic surveyors are experts at reconstructing costs using industry-standard valuation models. This thoroughness ensures your claim is both maximised and compliant.
For businesses involved in innovation, it's also worth exploring claiming R&D tax credits alongside your property claims. Combining these incentives can transform your tax position into a strategic asset. If you're ready to start the process, you can request a no-cost feasibility study to uncover the value hidden in your portfolio.
Why a Specialist Forensic Survey is Essential for Maximum Recovery
Identifying capital allowances on property isn't a task for general accounting software. Most platforms are designed to handle visible, invoiced assets like machinery or vehicles. They lack the forensic capability to look behind the walls of a commercial building. Whilst your general accountant is vital for day-to-day operations, they often lack the specialised surveying tools required to value 'embedded' items. Specialist surveyors amongst our team find hidden value that others overlook by meticulously deconstructing the property's cost into its qualifying components.
This process requires a unique dual expertise. It's the intersection of RICS-qualified surveying and specialist tax accounting. One side understands the physical engineering of the building; the other understands the evolving 2026 tax legislation. By combining these disciplines, we transform Capital Allowances into a strategic business asset. This isn't just about reducing a tax bill. It's about recovering capital to fuel your next phase of innovation or expansion.
The Recoup Capital Success-Based Approach
We believe in demonstrating value through results rather than traditional sales pitches. Our success-based fee model ensures our interests are perfectly aligned with yours. There are no upfront costs to worry about. We only generate a fee when we successfully identify and secure real tax savings for your business. This creates a stress-free environment where you can explore your eligibility without financial risk. The process is designed to be efficient, requiring minimal time from your internal team whilst we handle the technical complexities.
Protecting Your Claim Against HMRC Enquiries
Compliance is the cornerstone of our service. A detailed technical report acts as a protective shield during any potential HMRC enquiry. We provide the forensic evidence and legislative citations needed to justify every pound claimed. Using a firm with a proven track record in specialist tax relief ensures your claim is built on solid ground. Reliability and transparency are central to how we work. If you're ready to unlock the hidden capital in your portfolio, contact Recoup Capital today for a no-obligation feasibility study.
Transform Your Property Into a Strategic Financial Asset
The infrastructure of your commercial building holds significant untapped potential. By moving beyond standard accounting and utilising forensic expertise, you can identify the embedded fixtures that qualify for substantial relief. Navigating the current 2026 tax landscape, including the £1 million Annual Investment Allowance and the new 40% First-Year Allowance, is essential for maintaining a competitive edge. Securing capital allowances on property is about more than just tax compliance; it's a proactive strategy to improve cash flow and fuel business innovation.
Our team of specialist forensic surveyors and chartered tax accountants provides national UK expertise to ensure your claim is both maximised and robust. We operate on a success-based fee model; we only win when you save. This partnership-oriented approach removes the financial risk, allowing you to focus on your bottom line whilst we handle the technical details. You can book your no-obligation capital allowances feasibility study with Recoup Capital to start your journey toward capital recovery. Your property's hidden value is waiting to be discovered.
Frequently Asked Questions
Can I claim capital allowances on a property I bought years ago?
Yes, you can claim as long as you still own the property and the assets are in use. There's no fixed time limit for claiming on property you've owned for years, provided the previous owner didn't exhaust the claim. We often look back at historic acquisitions to identify qualifying fixtures that were overlooked at the time. This forensic look-back can unlock immediate tax relief for your current period, transforming old expenditure into a fresh strategic asset.
Do I need my original invoices to make a claim on embedded fixtures?
No, original invoices aren't strictly necessary for embedded items. Whilst they are helpful, our specialist surveyors use forensic techniques to reconstruct costs based on the building's age and condition at the time of purchase. We apply professional valuation models to determine a 'just and reasonable' cost for fixtures like cabling or heating systems. This ensures you don't lose out on savings simply because of missing paperwork from a previous owner or developer.
What is the difference between repairs and capital expenditure for tax?
Repairs are revenue expenditures that maintain an asset's current condition, like fixing a leaky pipe. Capital expenditure involves improving or replacing an asset, such as installing a completely new heating system. Repairs are typically deducted from profits in the year they occur. Conversely, capital allowances on property spread the relief over several years or provide a significant first-year deduction. This depends on the specific asset class and the current 2026 tax pool rates.
How much can I typically expect to recover from a commercial property claim?
Recovery amounts vary significantly based on the property type. For a standard office or retail unit, qualifying fixtures often represent between 10% and 40% of the purchase price. Specialist buildings like hotels or care homes can see even higher percentages due to the density of integral features. Our feasibility study provides a clear estimate of your potential recovery before we begin the full forensic survey, ensuring you understand the strategic value of the claim before proceeding.
Can I claim capital allowances if I am a tenant making improvements?
Yes, tenants can claim capital allowances on any qualifying plant and machinery they install during a fit-out or renovation. These are often referred to as tenant's fixtures. Provided you bear the cost of the installation and the items are used for your trade, you are entitled to the relief. This is a vital consideration for businesses moving into new premises, as the tax savings can significantly offset the initial cost of the improvement works.
What happens to my capital allowances when I sell the property?
When you sell, you must address the fixtures through a Section 198 election. This legal agreement fixes the value of the allowances transferred to the buyer. If you don't complete this step, you may lose the ability to retain any remaining relief, and the buyer might be barred from claiming in the future. It's a critical part of the transaction process that requires specialist coordination between your legal team and tax advisors to protect your long-term interests.
Is it possible to claim both R&D tax credits and capital allowances?
Yes, these are separate incentives that can be claimed together. Whilst capital allowances on property target the physical infrastructure of your building, R&D tax credits reward investment in innovation. If your firm conducts R&D within a specialised facility, you may be eligible for both. Our chartered tax accountants ensure that each claim is categorised correctly. This maximises your total relief whilst maintaining full compliance, helping you reinvest more capital back into your business growth.
How do the 2026 40% first-year allowances affect my current property purchase?
The 40% First-Year Allowance (FYA) launched in January 2026 provides a powerful front-loaded deduction for new main rate plant and machinery. If you're purchasing a property with brand-new fixtures, this allowance can significantly accelerate your tax relief. It's particularly beneficial for improving immediate cash flow compared to standard writing down rates. You must distinguish between new and second-hand fixtures, as different rules apply. Our forensic surveyors can help you categorise these assets to ensure maximum recovery.


