

Could your commercial property be hiding a six-figure tax windfall that your standard accounting software simply cannot see? You've likely already claimed for obvious items like desks and computers, and it's natural to assume your tax position is fully optimised. However, the most valuable tax relief often sits behind the walls and under the floorboards of your building. Understanding embedded capital allowances uk wide is about more than just bookkeeping; it's about forensic engineering and identifying the systems that keep your business running.
We understand that the prospect of an HMRC inquiry can feel daunting, especially when you're unsure what qualifies as an "integral feature" versus a standard fixture. This guide promises to clear that uncertainty, showing you how to unlock significant tax relief through specialist surveying and expert navigation of current legislation. We will explore the 2026 strategic landscape, including the new 40% first-year allowance and the permanent full expensing rules, ensuring you have the HMRC-compliant documentation needed to turn hidden assets into liquid capital for business innovation and growth.
Key Takeaways
- Identify why standard accounting practices often overlook the "hidden" tax relief woven into your building fabric and how to reclaim it.
- Navigate the 2026 tax landscape with confidence by understanding the new 40% first-year allowance and current writing down rates.
- Discover how forensic surveying uncovers embedded capital allowances uk wide that are frequently missed by generalist accountants.
- Protect your future claims by mastering the two-year rule and the essential mechanics of Section 198 elections during property transactions.
- Learn how a success-based model can transform recovered tax into a strategic asset for reinvestment and business growth.
Unlocking Hidden Value: Embedded Capital Allowances UK in 2026
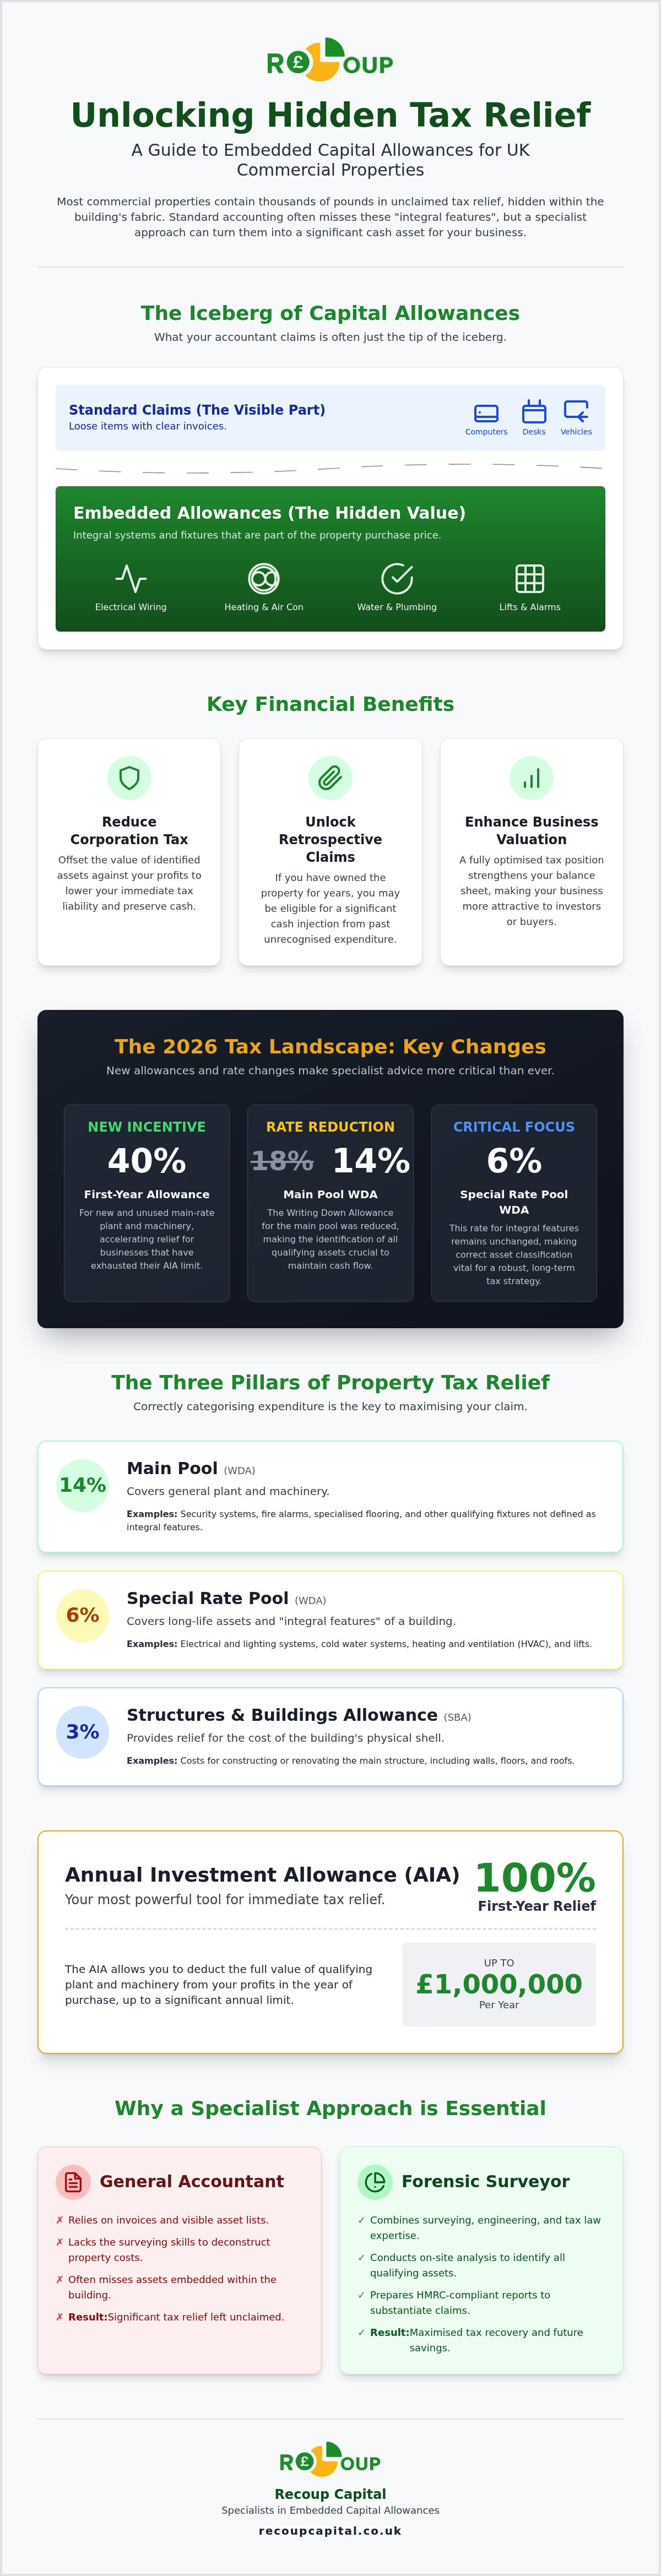
Most commercial property owners in the UK are sitting on a substantial, invisible reservoir of capital. While your accountant likely handles the obvious claims for desks, computers, and vehicles, a significant portion of tax relief remains trapped within the very fabric of your building. These embedded capital allowances uk wide represent the qualifying expenditure on "integral features" and fixtures that are essential to a building's functionality. A Capital allowance claim allows you to treat assets like heating systems, electrical wiring, and lifts as plant and machinery, effectively deducting their value from your taxable profits.
The reason these allowances are frequently overlooked is simple: standard accounting relies on visible invoices. When you purchase a freehold or leasehold property, the sale and purchase agreement rarely provides a granular breakdown of the internal components. It simply lists a total property price. Without a specialist forensic surveyor to deconstruct these costs, your business misses out on the chance to turn "dead money" into a strategic asset. We view this recovered tax not just as a refund, but as a vital tool for reinvestment and business innovation.
The Core Benefits for UK Limited Companies
Engaging with a specialised capital allowance review offers immediate and long-term financial advantages. By identifying these hidden fixtures, you can achieve an immediate reduction in your Corporation Tax liability through profit offsetting. It's a highly efficient way to preserve cash. For many businesses, the most exciting prospect is the potential for retrospective claims. If you've owned your property for years, you could be eligible for a significant cash flow injection from past expenditure. Additionally, ensuring your property's tax position is fully optimised can enhance the overall valuation of your business, making it a more attractive prospect for future investors or buyers.
The 2026 Legislative Landscape
The year 2026 has introduced pivotal shifts in how businesses must manage their property portfolios. A major update is the introduction of the 40% first-year allowance for new and unused main-rate plant and machinery, which became available on 1 January 2026. This allowance provides a powerful incentive for businesses that have already exhausted their £1,000,000 Annual Investment Allowance (AIA). It's a proactive measure designed to accelerate relief and encourage capital investment.
However, the landscape is also tightening. As of 1 April 2026, the Writing Down Allowance (WDA) for the main pool of plant and machinery was reduced from 18% to 14%. This reduction makes the 50% first-year allowance for special rate assets even more critical for maintaining healthy cash reserves. Because the special rate pool WDA remains at 6%, identifying every possible "integral feature" through capital allowances expertise is now the only way to ensure your tax strategy remains robust. 2026 is the year to move beyond basic bookkeeping and adopt a forensic approach to your property assets.
The Three Pillars of Property Tax Relief: Plant, Machinery, and Structures
To successfully claim embedded capital allowances uk, your expenditure must be accurately allocated across three primary categories. Each category carries a different rate of relief, and misclassification can lead to either missed opportunities or unwanted scrutiny from HMRC. Understanding where your property investment sits within these "pillars" is the first step toward effective capital recovery.
The main pool typically covers plant and machinery. Following the legislative adjustments in April 2026, the Writing Down Allowance (WDA) for this pool now sits at 14%. The special rate pool, which covers integral features such as electrical and water systems, attracts a 6% WDA. For the building's physical shell, the Structures and Buildings Allowance (SBA) provides a steady 3% annual relief on qualifying costs. For businesses seeking immediate impact, the Annual Investment Allowance (AIA) remains a vital tool, offering 100% first-year relief on qualifying plant and machinery expenditure up to a limit of £1,000,000 per year.
Plant and Machinery: Identifying Qualifying Assets
Main pool assets aren't always loose items like laptops or machinery. Within the building fabric, items such as security systems, fire alarms, and even specialised flooring can qualify for the 14% WDA. The "function test" is the gold standard here. It asks a simple question: does the item perform a specific function essential to the business, or is it merely part of the setting? If a floor is specifically reinforced to support heavy equipment, it may transition from a "structure" to "plant," unlocking faster relief. If you're looking to identify these hidden assets, a specialist review of your capital allowances can reveal significant untapped value.
Integral Features: The Special Rate Pool
Integral features are the systems that make a commercial building habitable and functional. This pool includes electrical systems (including lighting), cold water systems, and climate control like space or water heating. Lifts, escalators, and even thermal insulation added to existing buildings also fall into this 6% category. While the 6% rate is lower than the main pool, companies can often claim a 50% first-year allowance for special rate assets in the period of purchase. Correctly distinguishing between a "fixture" and an "integral feature" is often where generalist accounts fail, as the line between them can be thin and requires a surveyor's eye to define accurately.
Forensic Surveying: Identifying Assets Your Accountant Might Miss
It's a common misconception that a standard year-end tax return captures every available relief. Many business owners tell us, "My accountant has already claimed everything possible," and whilst their accountant is likely excellent at managing visible expenditure, they rarely have the surveying expertise to look behind the walls. A typical accountant works from invoices and receipts. If an invoice simply says "Property Purchase" or "Refurbishment Works," the specific qualifying components remain invisible. This data gap is where embedded capital allowances uk claims are frequently lost.
A specialist forensic surveyor doesn't just review your ledger; they physically inspect the property to unbundle construction costs that your accountant simply cannot see. A desk-based review might identify a new boiler, but a physical site inspection identifies the entire distribution network, the specialised control systems, and the bespoke ventilation that qualifies for relief. This level of detail is the difference between a modest claim and a transformative cash injection. We don't just process paperwork; we uncover the physical reality of your investment, much like how professional Rebuild Costs assessments provide an accurate picture of a building's reinstatement value for insurance purposes.
The Gap Between Accounting and Forensic Surveying
The fundamental difference lies in how assets are identified. General accountants look at invoices; forensic surveyors look at the building fabric. When a construction project is completed, the final bill often arrives as a single, large sum. Without a surveyor's ability to deconstruct that figure into its constituent parts, such as electrical cabling, fire safety systems, and thermal insulation, the business significantly under-claims. Forensic surveying is the bridge between tax law and physical asset identification.
Case Study: Common Hidden Assets
Consider a modern office environment. Beyond the desks and computers, there is acoustic glazing, specialised lighting systems, and integrated climate controls. In the hospitality and manufacturing sectors, the opportunities are even greater. Complex plumbing and drainage systems, which are essential for operations, are frequently missed because they are "embedded" within the structure. By applying a forensic lens to your property, you can begin identifying hidden savings that have been sitting on your balance sheet for years. Our role is to act as your protective guide, ensuring that your embedded capital allowances uk strategy is both exhaustive and fully compliant with HMRC standards.
Navigating Transactions: Section 198 Elections and the Two-Year Rule
The point of purchase or sale is the most critical moment for embedded capital allowances uk. If the correct legal mechanisms aren't triggered during the transaction, the right to claim can be permanently lost. Central to this process is the Section 198 election. This is a formal agreement between the buyer and seller that "fixes the value" of fixtures being transferred. You generally have a strict two-year window from the date of completion to submit this election to HMRC. Missing this deadline often means the allowances are lost to both parties forever, regardless of the property's value.
Since April 2014, the "pooling requirement" has added another layer of complexity. It dictates that a seller must have identified and "pooled" the allowances in their own tax returns before they can pass them to a buyer. If the seller has failed to do this, the buyer is legally barred from claiming on those specific assets in the future. This creates a high-stakes environment where specialist advice is mandatory rather than optional. We act as a protective guide during these negotiations, ensuring that the tax narrative of the building is preserved and passed on correctly.
Buying a Commercial Property: Due Diligence
When acquiring an asset, your legal team will review the Commercial Property Standard Enquiries (CPSE) forms. These documents reveal the prior claim history of the seller. You must establish whether the seller has already claimed, as this dictates what is left for you to recover. Negotiating the value in the Section 198 election is a key part of the deal. A higher value benefits your future tax relief, whilst a lower value might suit the seller's disposal strategy. Failing to address this early can lead to a significant loss of potential cash flow that could have been reinvested into your business operations.
Selling a Commercial Property: Retaining Value
If you are selling, don't view your capital allowances as a mere footnote. They are a powerful negotiation tool. By demonstrating the value of unclaimed allowances to a buyer, you can often justify a higher final sale price. Conversely, "giving away" these allowances without a clear tax strategy can lead to unnecessary balancing charges that increase your own tax bill upon disposal. It is also worth considering how these figures impact on Stamp Duty Land Tax calculations during the transfer. To ensure you aren't leaving money on the table during your next transaction, you can request a specialist transaction review to protect your interests.
From Tax Relief to Strategic Growth: The Recoup Capital Approach
Securing embedded capital allowances uk wide shouldn't be a source of stress or a distraction from your core operations. We believe that professional financial consultancy should be defined by results rather than traditional sales pitches. Our success-based fee model is designed to remove upfront risk, ensuring that our interests are perfectly aligned with your business goals. If we don't identify qualifying expenditure, you don't pay a fee. It's a transparent, partnership-oriented approach that prioritises your bottom line over paperwork.
Our end-to-end process is built for efficiency and compliance. We begin with an initial forensic assessment of your property portfolio to gauge potential value. This is followed by a physical site inspection by our specialist surveyors, who unbundle the construction costs often missed by standard accounting. Once the forensic report is complete, our chartered tax accountants handle the final HMRC liaison, providing you with a robust, fully documented claim that stands up to scrutiny. We take care of the technical heavy lifting so you can focus on running your business.
A Partnership, Not a Pitch
We don't aim to replace your existing accountant; we work alongside them to add a layer of specialised forensic value that generalist practices rarely offer. Whilst your accountant manages your annual compliance, we provide the deep-dive surveying expertise necessary to uncover hidden fixtures within the building fabric. In the complex 2026 tax market, this result-driven consultancy is essential for ensuring no stone is left unturned. Recoup Capital transforms tax compliance into a strategic growth opportunity.
The Holistic Tax Recovery Strategy
For many businesses, capital allowances are just one piece of a larger innovation puzzle. Our team looks at your business holistically, identifying how property relief can integrate with other incentives such as R&D tax credits. For developers or those refurbishing brownfield sites, we also explore the potential for Land Remediation Relief to maximise your total recovery. By reframing these tax returns as strategic assets, you can secure the capital needed to fund future R&D projects or expand your operations.
The 2026 landscape offers significant opportunities for those who act decisively. Whether you are looking to offset Corporation Tax or inject fresh cash into your business, a specialised review of your embedded capital allowances uk assets is the first step. We invite you to reach out for a no-obligation specialist property review to discover the hidden value waiting within your commercial assets.
Maximising the Strategic Value of Your Commercial Portfolio
The 2026 tax landscape has evolved, making it more critical than ever to look beyond standard accounting for embedded capital allowances uk. We've explored how forensic surveying bridges the gap between physical assets and tax legislation, ensuring that no qualifying fixture is left unclaimed. Whether you're navigating the complexities of a Section 198 election or looking to utilise the new 40% first-year allowance, the right specialist guidance transforms these regulatory requirements into a powerful engine for business growth.
At Recoup Capital, our success-based fee model ensures you can explore these opportunities without upfront risk. Our team of chartered tax accountants and forensic surveyors provides HMRC-compliant forensic reporting that stands up to the most rigorous scrutiny. We don't just process claims; we build long-term partnerships that turn hidden relief into strategic capital. It's time to stop leaving money in the walls and start reinvesting in your future.
Book your no-obligation capital allowance review with our specialists to unlock the hidden value in your property today.
Frequently Asked Questions
What are embedded capital allowances for commercial property?
Embedded capital allowances are tax reliefs available on the fixtures and integral features "embedded" within a commercial building's fabric. These include essential systems like cabling, lighting, heating, and security. Unlike movable assets, these items are legally part of the property. Identifying embedded capital allowances uk wide allows businesses to deduct a percentage of these costs from their taxable profits, effectively reducing their Corporation Tax liability.
Can I claim capital allowances on a property I have owned for years?
You can often make retrospective claims on properties you have owned for many years, provided you still own the assets and use them for your trade. There is no strict time limit for claiming on assets you still own within the business. However, the value of the claim will depend on the specific tax rules and rates in place at the time of the original purchase or installation.
What is the difference between fixtures and chattels in UK tax law?
The distinction lies in how an item is attached to the building. Fixtures are items that are legally part of the property, such as lifts, toilets, or air conditioning systems. Chattels are movable items like office chairs, loose tools, or computers. Whilst accountants easily identify chattels from invoices, fixtures require a specialist surveyor to separate their cost from the overall property purchase price or construction bill.
Is my accountant already claiming these allowances for my business?
Your accountant is likely claiming for visible assets like furniture and IT equipment, but they may miss the hidden fixtures. Standard accounting relies on itemised invoices, which are rarely available for the internal components of a building purchase. Forensic surveyors are needed to unbundle these costs from the total purchase price. We work alongside your accountant to provide the technical surveying data they need to optimise your tax position.
How much does a specialist capital allowance claim cost?
We operate on a success-based fee model, which means there are no upfront costs for our clients. You only pay a fee if we successfully identify and secure tax relief for your business. This approach removes the financial risk and ensures our interests are fully aligned with yours. We focus on delivering value through results, transforming the claim process into a risk-free opportunity for capital recovery.
What happens if I sell my commercial property after making a claim?
When you sell a property, you must enter into a Section 198 election with the buyer to determine how much of the claim value is transferred. If you have already claimed, you may be able to retain the benefit of those embedded capital allowances uk or use them as a negotiation tool to increase the sale price. Failing to address this during the transaction can lead to a balancing charge, effectively repaying some of the relief to HMRC.
Can I claim capital allowances on a leased commercial building?
Leaseholders can claim capital allowances on the expenditure they incur for fit-outs, refurbishments, or improvements. If you have paid for the installation of air conditioning, partitions, or kitchen facilities in a rented space, those assets belong to you for tax purposes. These claims are an excellent way for tenants to recover a portion of their capital investment and improve their business cash flow.
How long does the forensic surveying process typically take?
The end-to-end process typically takes between four and eight weeks from the initial instruction to the final report submission. This timeframe includes the physical site survey, the forensic analysis of costs, and the preparation of HMRC-compliant documentation. We aim for a streamlined experience that requires minimal input from your team, allowing you to stay focused on your daily operations whilst we secure your relief.


