

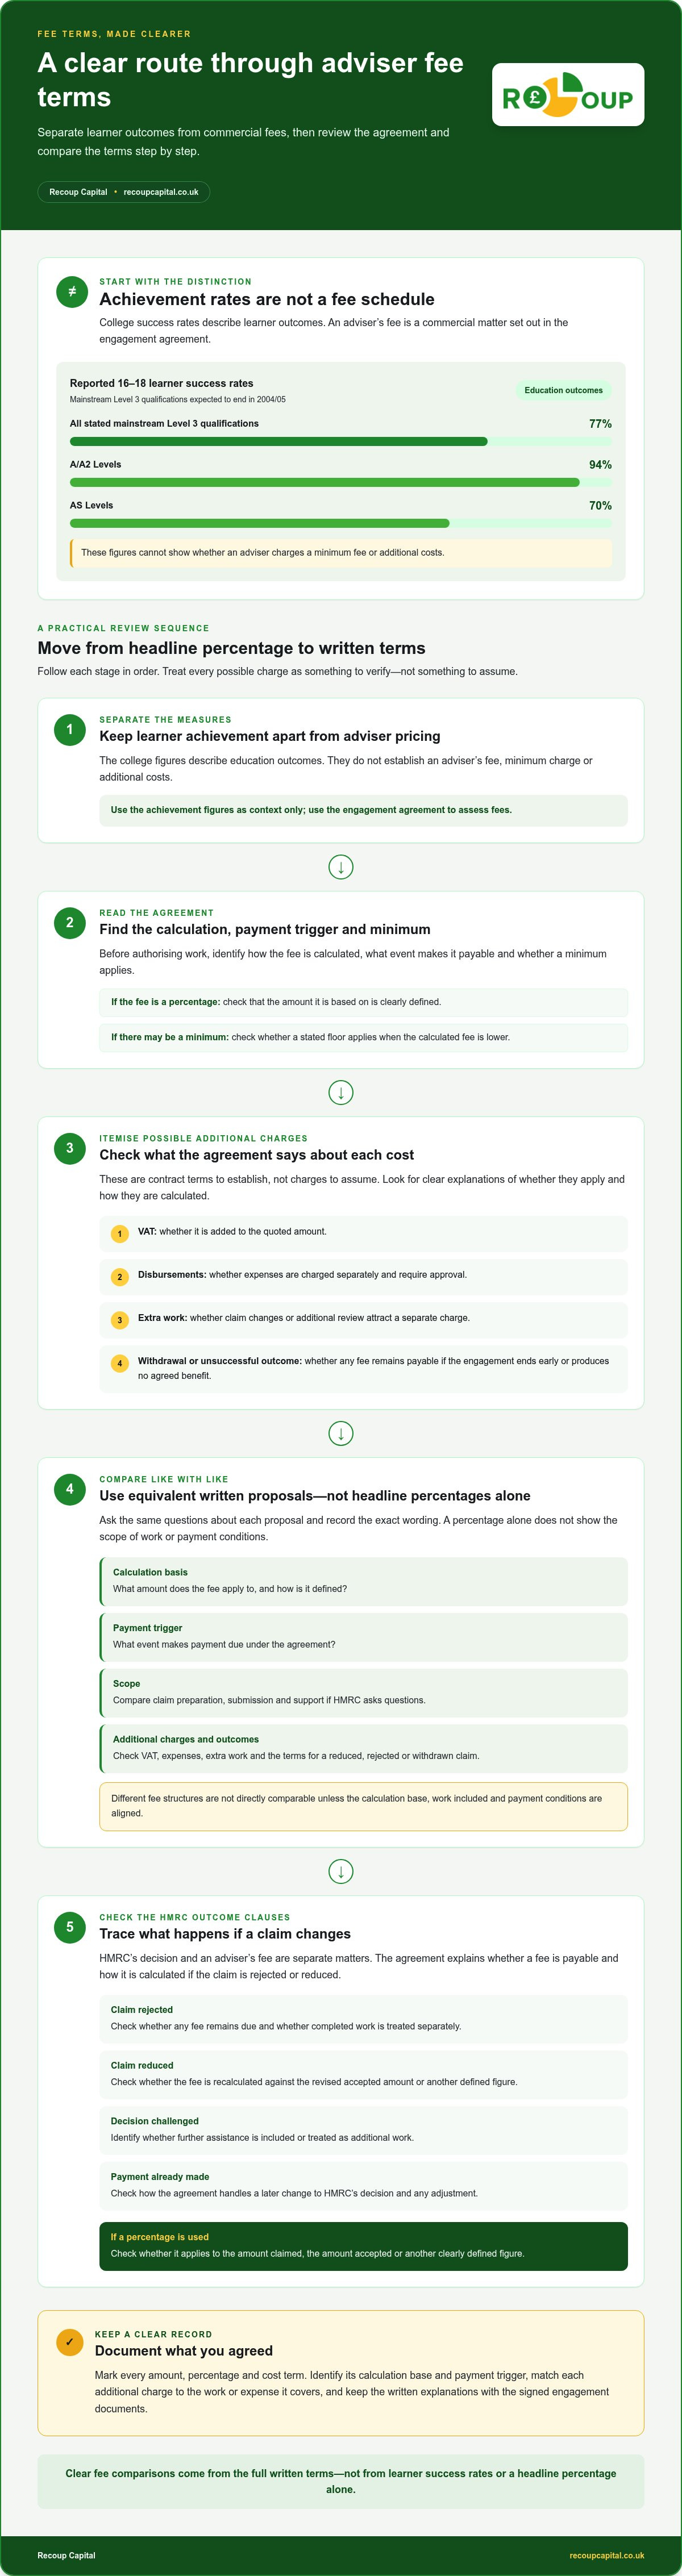
Learner achievement and a Recoup Capital success fee measure different things: college success rates describe learners’ outcomes, while a fee is a commercial matter. At the institution, 16-18 learners achieved a 77% success rate on mainstream Level 3 qualifications expected to end in the academic period. Their success rates were 94% for A/A2 Levels and 70% for AS Levels.
It’s natural to ask how leadership and management affect learner outcomes, especially when success rates are used to measure performance. The figures are a starting point, but they need to be understood in the wider context of achievement.
This article explains how leadership, management and learner achievement relate to the Recoup Capital success fee topic. It also clarifies what education success rates can show and how they differ from a commercial fee arrangement.
Key Takeaways
- Separate learner achievement measures from an adviser’s commercial fee: they describe different things.
- Find out which fee terms and possible additional charges apply before comparing adviser proposals.
- Understand how the engagement agreement treats a claim that HMRC reduces or rejects.
- See how Recoup Capital’s R&D Tax Credits support may fit when your business is preparing an innovation claim.
Are there minimum fees or additional charges with Leyton?
Learner achievement figures and adviser fees answer different questions. Leyton Sixth Form College’s 16-18 learners achieved a 77% success rate on mainstream Level 3 qualifications expected to end in 2004/05. That education result is not a fee schedule and cannot show whether a consultancy charges a minimum fee or additional costs.
When considering a Leyton success fee, start with the written engagement agreement. Read it before authorising work, and check how the fee is calculated, what triggers payment and whether a minimum applies. If the fee is a percentage, the agreement should clearly define the amount it is based on. Don’t treat “success fee” as a complete description of the payment terms.
Check whether the agreement lists additional charges and explains how they are calculated. It should make clear whether any of these apply:
- Minimum fee: whether a stated floor applies even when the calculated fee is lower.
- VAT: whether it is added to the quoted amount.
- Disbursements: whether expenses are charged separately and require approval.
- Extra work: whether changes to the claim or additional review attract a separate charge.
- Withdrawal or unsuccessful outcome: whether any fee remains payable if the engagement ends early or produces no agreed benefit.
These are contract terms to establish, not charges to assume. For example, if a proposal gives a percentage but says nothing about VAT or expenses, ask for the full cost basis in writing before signing. Compare the response with the engagement terms instead of relying on the headline percentage alone.
Review the proposal methodically. Mark every amount, percentage and cost term, then identify the calculation base and the event that triggers payment. Match each additional charge to the work or expense it covers, and keep the agreed schedule with the signed engagement documents. This gives your finance team a clear record for budgeting and checking invoices.
The central point is straightforward: the 77% college achievement figure describes learner outcomes, while minimums and extra charges depend on the commercial terms being reviewed. A written fee breakdown lets you assess those terms directly, without confusing educational success measures with adviser pricing.
A minimum fee or additional charges depend on the written engagement agreement, so don’t assume they apply. Check whether the agreement sets a minimum and explains VAT, disbursements, extra work, or fees for withdrawal or an unsuccessful outcome.
How does Leyton’s fee compare with other UK R&D tax credit advisers?
To compare fees fairly, use written proposals covering equivalent work. A headline percentage alone cannot show which arrangement offers better value. Compare the calculation basis, included work and payment conditions, rather than assuming UK advisers use identical terms.
Ask the same questions about every proposal. This makes the differences easier to see without relying on an unsupported market average or treating a marketing claim as proof of value.
- Calculation basis: identify the amount the fee applies to and how it is defined.
- Payment trigger: note the event that makes payment due under the agreement.
- Scope: compare claim preparation, submission and support if HMRC asks questions.
- Additional charges: check how VAT, expenses or extra work are treated.
- Outcome terms: see what the agreement says about a reduced, rejected or withdrawn claim.
For example, one proposal might state a percentage but cover limited work, while another might use a different fee structure and include a broader scope. Their headline figures aren’t directly comparable unless the calculation base, work included and payment conditions are aligned.
Create a comparison table with a row for each term above. Record the exact wording from every proposal, then note differences in scope or payment triggers. If a clause could affect the cost, ask for a written explanation before signing. Keep the response with the proposal so your finance team can refer to the agreed terms later.
Assess value as well as cost. Consider how clearly the adviser describes the work, what support is included and how the agreement handles changes to the claim. A higher or lower headline percentage does not, by itself, show which proposal better fits your business.
The heading alone cannot support a reliable comparison. Put current proposals side by side, using consistent criteria and the full contractual wording. This lets you assess the terms offered without assuming that one adviser’s calculation or scope matches another’s.
What happens to Leyton’s fee if an HMRC claim is rejected or reduced?
HMRC’s decision and an adviser’s fee are separate matters. The engagement agreement explains whether a fee is payable, how it is calculated and what happens if a claim is rejected or reduced. Don’t assume the phrase “success fee” settles these terms.
Before signing, read the clauses about outcomes. Find the fee calculation basis, the event that triggers payment and any process for revising an invoice if HMRC changes its decision. If the agreement uses a percentage, check whether it applies to the amount claimed, the amount accepted or another defined figure.
- Claim rejected: look for wording explaining whether any fee remains due and whether work already completed is treated separately.
- Claim reduced: check whether the fee is recalculated against the revised accepted amount or remains based on another figure.
- Decision challenged: identify whether further assistance is included or treated as additional work.
- Payment already made: check how the agreement handles a later change to HMRC’s decision and any adjustment.
For example, an agreement might make payment conditional on a specified outcome. If HMRC then reduces the claim, the clause determines whether the fee changes. Another agreement might set a different trigger or calculation base. Compare the written terms, rather than relying on assumptions about what a success-based arrangement usually means.
Keep the HMRC decision, claim calculation, adviser correspondence and invoice together. If the decision differs from the amount used to calculate the fee, check each figure against the agreement. Ask for an itemised explanation that identifies the relevant clause and calculation. This creates a clear record for your finance team and helps resolve discrepancies using the agreed terms.
Before appointing an adviser, ask for the proposal or agreement to explain what happens if a claim is rejected or reduced. Confirm who handles HMRC follow-up, what that work includes and whether it affects the fee. Clear terms help you assess your exposure before work begins and understand the next steps if HMRC questions the claim.
For practical guidance on preparing an R&D claim, review the R&D claim process alongside the fee terms. The agreement remains the key reference for deciding how a particular HMRC outcome affects payment.
Recoup Capital: R&D Tax Credits
Recoup Capital helps limited companies assess and claim R&D tax credits for innovation activity. Its specialists can support you as you review project costs, gather evidence and prepare a claim for HMRC. A clear account of the work undertaken and the supporting evidence helps shape a well-founded claim.
If you need guidance on how your business’s development work may fit an R&D claim, this is a practical next step. The process connects eligible innovation activity with a claim, so you can consider potential tax relief as part of wider business planning.
To discuss R&D tax credits for your business, contact Recoup Capital or visit recoupcapital.co.uk.
Turn clear fee terms into a considered next step
A Leyton success fee discussion can prompt you to look beyond the fee and consider how your company funds innovation and planned investment. Start by recording development work, major asset purchases and any land remediation activity. This gives management a practical basis for deciding which tax reliefs to explore, rather than treating each opportunity in isolation.
Recoup Capital offers R&D Tax Credits, Capital Allowances and Land Remediation Relief. These are separate areas, and the relevant option depends on your business’s activities and plans. A focused discussion can help you identify which topics align with your priorities and what information to bring. Keep project notes, expenditure records and investment plans together to give the conversation a clear commercial starting point.
If you’re ready to explore the next step, contact Recoup Capital to discuss your options. A clear view of your projects and investment plans can help make that conversation productive and keep future growth in focus.
Frequently Asked Questions
How does Leyton calculate its success fee?
The written engagement agreement sets the fee calculation basis and the event that triggers payment. If the fee is a percentage, the agreement should define the amount it applies to.
What is included in Leyton’s success fee?
The agreement should define the work covered, such as claim preparation, submission and support if HMRC asks questions. Check whether additional work is charged separately.


