

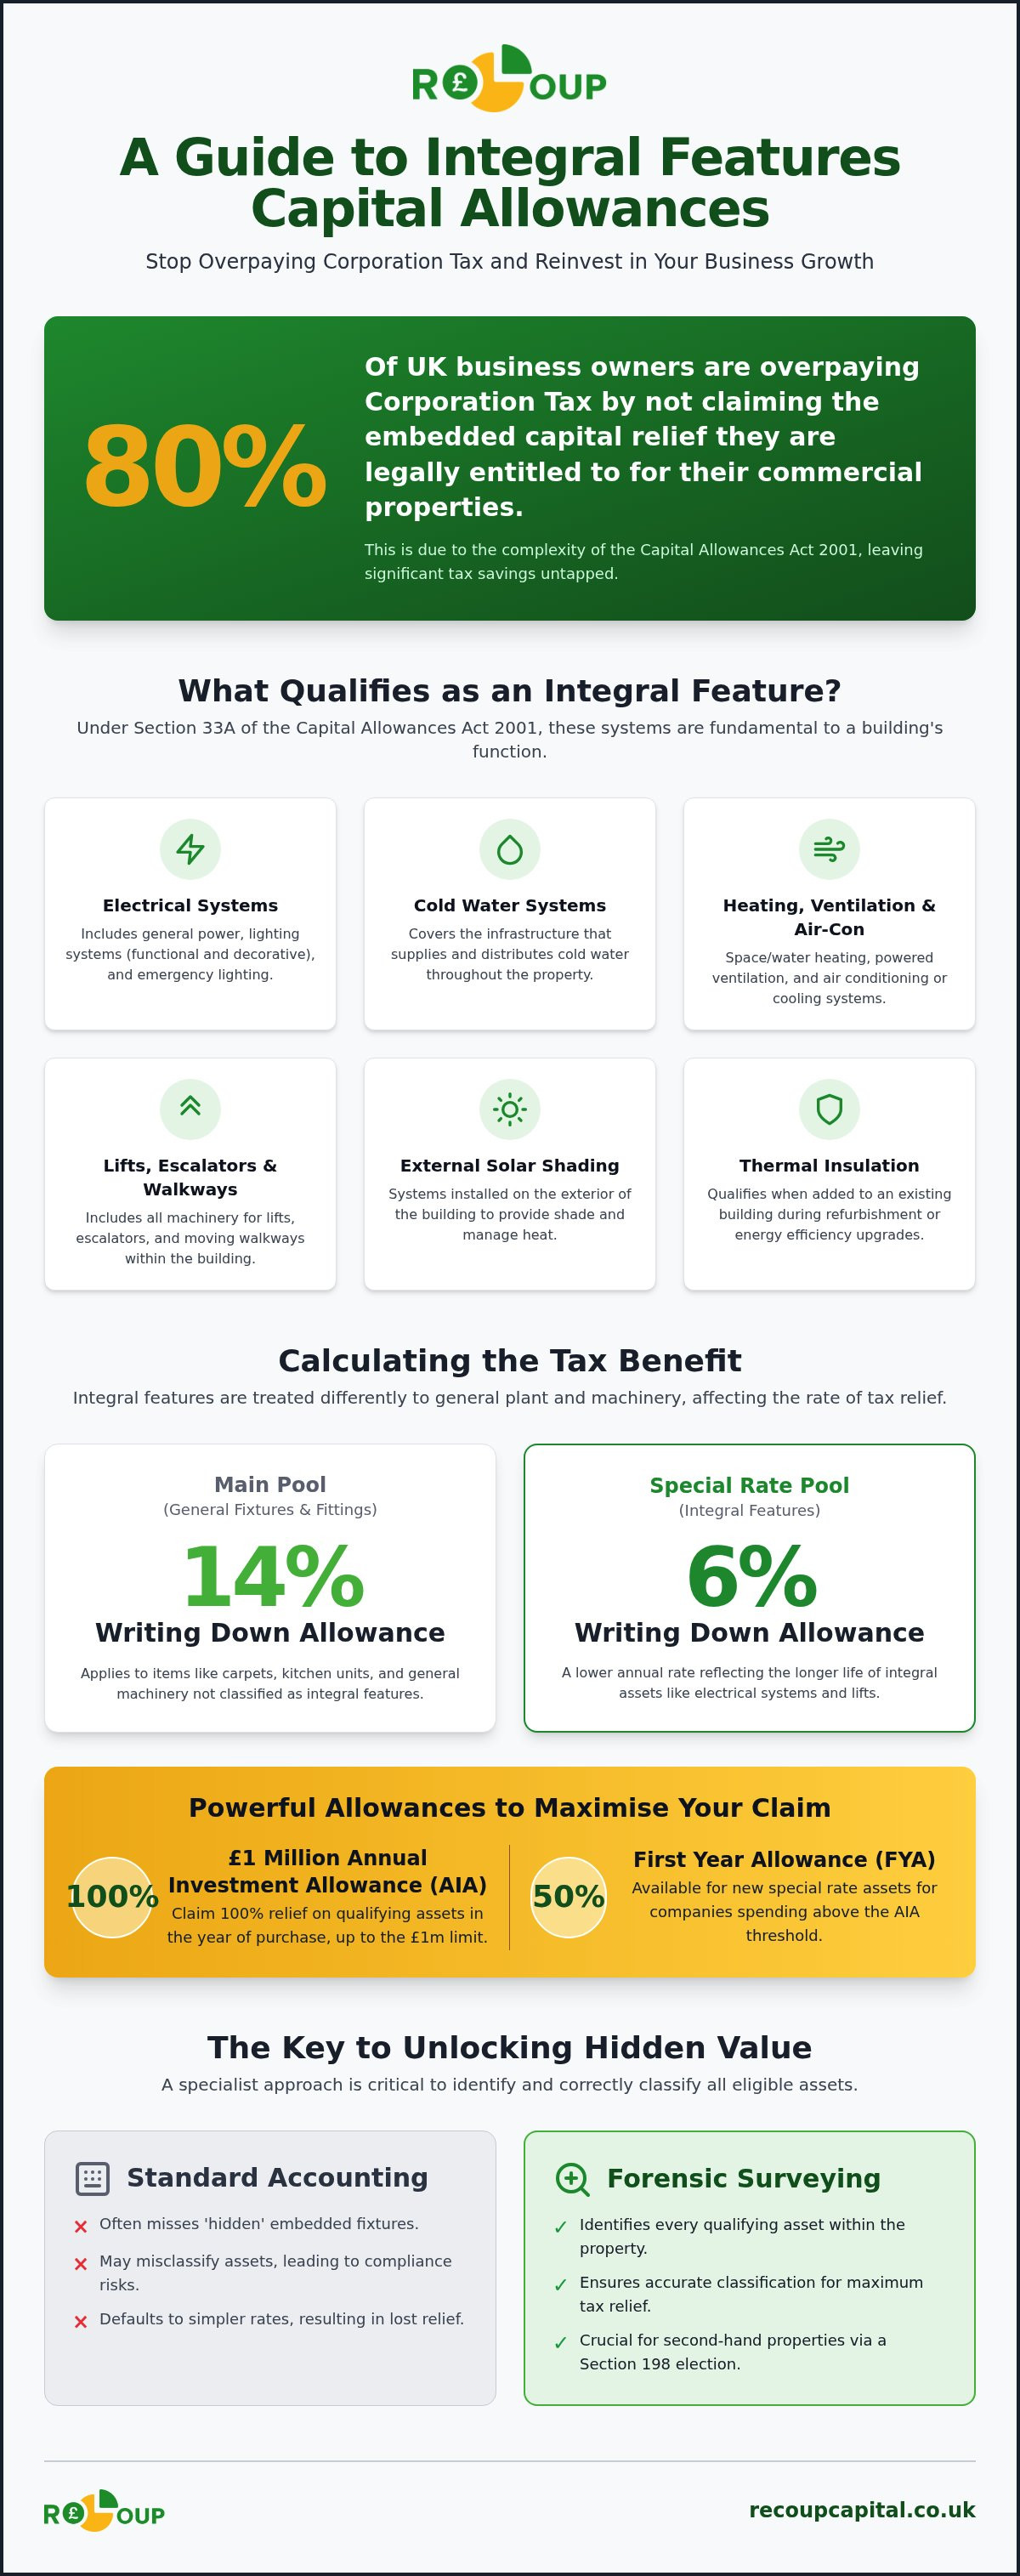
Did you know that roughly 80% of UK business owners are overpaying their Corporation Tax simply because they haven't claimed the embedded relief they're legally entitled to? It's a staggering figure that highlights a common frustration amongst commercial property owners. You likely already suspect that your building holds more value than what's on the surface, yet the sheer complexity of the CAA 2001 legislation makes it difficult to know where to start. Distinguishing between main pool assets and integral features capital allowances shouldn't feel like a regulatory hurdle that drains your resources.
We're here to change that narrative by transforming these technical requirements into a clear opportunity for capital recovery. This guide provides the clarity you need to identify qualifying assets, from electrical systems to thermal insulation, and explains how the 6% Special Rate writing down allowance functions in the 2026 tax year. You'll discover how to leverage the £1 million Annual Investment Allowance and why a forensic survey is the key to uncovering hidden tax savings. By the end of this article, you'll have a roadmap to stop overpaying and start reinvesting that recovered capital back into your business growth.
Key Takeaways
- Identify which specific assets qualify under Section 33A of the Capital Allowances Act 2001, including electrical, water, and cooling systems.
- Master the mechanics of integral features capital allowances to effectively navigate the 6% Special Rate pool and maximise the £1 million Annual Investment Allowance.
- Learn why second-hand property acquisitions require a Section 198 election to secure significant tax relief that would otherwise be lost to the Exchequer.
- Recognise the critical difference between standard accounting and forensic surveying in identifying "hidden" embedded fixtures within your commercial building.
- Understand how to reframe recovered tax as a strategic business asset that can be reinvested into your company's future innovation and growth.
What are Integral Features in Capital Allowances?
Understanding integral features capital allowances begins with a shift in perspective. Instead of viewing a commercial property as just four walls and a roof, think of it as a living entity. The assets that allow that entity to function; the electrical systems, water supplies, and climate control; are classified specifically under Section 33A of the Capital Allowances Act 2001. These aren't just "extras" or furniture. They're assets fundamentally integrated into the fabric of the structure itself.
In the 2026 tax landscape, correctly identifying these features is essential for UK limited companies looking to optimise their balance sheets. Whilst many business owners assume all plant and machinery falls into a single category, the legislation creates a clear distinction for items that provide the building with its core utility. This distinction directly dictates how quickly you can recover your investment through tax relief. It transforms what might look like a standard utility cost into a strategic financial asset; to see how such assets fit into a broader wealth strategy, you can check out Kotini & Kotini.
The Special Rate Pool Explained
Most capital expenditure on plant and machinery qualifies for a 14% Writing Down Allowance (WDA) in the main pool, following the rate change in April 2026. However, integral features sit within the Special Rate pool, which attracts a 6% WDA. This lower rate reflects the longer life expectancy of these assets. Despite the lower annual rate, the strategic use of the £1 million Annual Investment Allowance (AIA) remains a powerful tool. It allows businesses to claim 100% relief on qualifying integral features capital allowances in the year of purchase, provided the total expenditure stays within the limit. For companies exceeding this threshold, a 50% First Year Allowance (FYA) remains available for new special rate assets.
Integral Features vs. General Fixtures
Confusion often arises when trying to separate a "fixture" from a legally defined "integral feature." A fixture might be a fitted carpet or a kitchen unit, which typically qualifies for the main pool's higher 14% rate. In contrast, an integral feature is something like a space heating system or a lift. Misclassifying these can lead to significant compliance risks or, more commonly, missed opportunities for relief. Non-specialist accountants often default to the main pool for simplicity, but a forensic approach ensures every asset is placed in the correct pool to protect your long-term tax trajectory. Understanding this nuance is a core part of managing your capital allowances strategy effectively without leaving money on the table.
The Definitive List: What Qualifies as an Integral Feature?
Identifying exactly what qualifies for tax relief requires more than a cursory glance at your building's blueprints. The list of assets is strictly defined by statute, leaving little room for interpretation. According to HMRC's definition of integral features, these systems are deemed to be part of the building but remain eligible for integral features capital allowances. It is a comprehensive list that covers the 'nervous system' of your commercial property, and failing to capture these during a property purchase or renovation often results in thousands of pounds in unclaimed relief.
The statutory list includes:
- Electrical systems (including lighting systems)
- Cold water systems
- Space or water heating systems, powered systems of ventilation, air conditioning or air cooling, and systems of a similar nature
- Lifts, escalators, and moving walkways
- External solar shading
- Thermal insulation on an existing building
Even items like thermal insulation, which many assume are part of the building's structure, qualify if they are added to an existing property during a refurbishment or energy-efficiency upgrade. This distinction is vital for businesses looking to modernise their premises whilst minimising their tax liabilities.
Electrical and Lighting Systems
Not every wire in your wall is treated the same way. Whilst general power systems and lighting are standard inclusions, distinguishing between general wiring and specific plant machinery is where many claims fail. Lighting systems are almost always classified as integral features, regardless of whether they are functional or decorative. Emergency lighting qualifies under CAA 2001 as it constitutes a system for providing light within a building. This classification ensures that even safety-critical infrastructure contributes to your tax recovery strategy. It's often these 'hidden' electrical components that provide the bulk of a claim in modern office blocks.
HVAC and Water Systems
The inclusion of cold water systems was a landmark change in the legislation, as these were previously excluded from many claims. Now, the entire system for distributing water throughout the building is eligible, though you must exclude the final delivery points like kitchen and bathroom taps. Similarly, any system designed for thermal regulation; including air conditioning and sophisticated ventilation; falls squarely into the category of integral features capital allowances.
Getting these distinctions right is the difference between a standard tax return and a forensic recovery. If you're unsure if your recent fit-out or property acquisition qualifies, it's worth taking the time to review your capital allowances strategy with a specialist surveyor who understands the nuances of the Special Rate pool. This proactive approach ensures you're not just following the rules, but actively using them to bolster your business's cash flow.
Main Pool vs. Special Rate: Calculating the Benefit
The distinction between the Main Pool and the Special Rate pool isn't just a matter of accounting labels. It's a fundamental driver of your company's cash flow. Following the legislative updates in April 2026, the Writing Down Allowance (WDA) for the main pool stands at 14%. In contrast, integral features capital allowances are allocated to the Special Rate pool, which attracts a 6% WDA. Whilst the 6% rate might seem less attractive, the strategic application of allowances can front-load your tax relief and unlock significant capital for reinvestment. Understanding this hierarchy is essential for any business owner looking to move beyond basic compliance toward true financial optimisation.
For a detailed breakdown of how these pools interact with your wider tax strategy, you can consult a practical guide to capital allowances. This classification dictates your balance sheet's trajectory for years. Misallocating an asset doesn't just invite HMRC scrutiny; it can trap capital in a slow-release tax pool when it could have been utilised immediately to fund innovation or expansion.
The Role of the Annual Investment Allowance (AIA)
The Annual Investment Allowance remains the most powerful tool in your tax planning arsenal. With the AIA limit permanently set at £1 million, most UK businesses can claim 100% relief on qualifying plant and machinery in the year of purchase. Smart tax planning requires you to prioritise your AIA for special rate assets first. Since integral features capital allowances only provide a 6% return through the standard WDA, using your AIA to cover these costs first ensures you receive the full tax benefit immediately. You then apply any remaining AIA to main pool assets, which would otherwise recover at the faster 14% rate anyway. This simple shift in logic can significantly boost your year-one tax savings.
Full Expensing and Integral Features
Limited companies investing in new and unused assets can also benefit from Full Expensing rules. Whilst main rate assets enjoy a 100% first-year deduction, special rate assets, including most integral features, qualify for a 50% first-year allowance. This is particularly valuable for large-scale construction projects where expenditure exceeds the £1 million AIA threshold. After claiming the initial 50%, the remaining balance enters the special rate pool to be written down at the standard 6% rate in subsequent years. It's a complex interaction that requires a specialist's eye to navigate correctly. You can learn more about managing these claims on our capital allowances service page, where we detail how to balance these incentives for maximum impact.
Identifying Hidden Relief in Existing Commercial Properties
Many UK business owners view the purchase price of a second-hand commercial property as a single, static figure. This perspective is a missed opportunity. In reality, these acquisitions are often a "gold mine" for integral features capital allowances. Because previous owners may not have claimed the full extent of the relief available, or perhaps they owned the building before the significant legislative shifts in 2008 and 2014, substantial value remains trapped within the structure. Expert data suggests it's possible to recover up to 40% of a property's purchase value through specialist forensic surveying for embedded capital allowances. This isn't just about finding tax breaks; it's about identifying assets you've already paid for but haven't yet utilised to reduce your tax burden.
The Forensic Surveying Process
Uncovering this value requires moving beyond standard invoices and basic accounting records. A forensic survey isn't just a paper exercise. It's a physical inspection of the premises to identify assets that don't appear on a basic bill of sale. A site visit is essential to satisfy HMRC compliance standards. It allows specialists to document the exact specification of electrical systems, thermal insulation, and HVAC units. This level of detail provides the robust evidence needed to support a historic claim, ensuring the valuation is defensible during any future tax enquiry. Without this documentation, thousands of pounds in relief could remain unclaimed indefinitely.
The Section 198 Election Trap
The most critical hurdle in second-hand transactions is the Section 198 election. This legal requirement dictates that the buyer and seller must agree on the value of fixtures at the point of sale. You have a strict two-year deadline from the date of transfer to formalise this agreement. If your legal team lacks specific tax expertise, they might agree to a nominal £1 value just to simplify the deal. Doing so permanently voids your ability to claim integral features capital allowances on those assets. It's a mistake that costs businesses dearly every year.
Poor advice during a property transfer is the leading cause of lost tax relief. It's vital to ensure that the "Fixed Value Requirement" is met accurately to protect your future cash flow. If you've recently acquired a commercial building or are in the process of a transaction, you can learn more about the capital allowances claim process to avoid these common pitfalls. Securing the right specialist input early transforms a standard property purchase into a strategic tax-saving event for your business.
Maximising Your Claim with Recoup Capital
Unlocking the full potential of integral features capital allowances requires a blend of chartered tax expertise and forensic surveying. Whilst your general accountant is vital for your day-to-day compliance, they often lack the specialist surveying tools needed to identify assets embedded within the property's structure. We bridge this gap. Our approach is designed to be entirely partnership-oriented, acting as a protective guide through complex HMRC regulations. By employing a success-based fee model, we ensure our goals are perfectly aligned with your tax savings. You don't pay for a report; you pay for results that can be reinvested directly into your business innovation.
Our team manages the end-to-end process, from the initial site visit to the final HMRC submission. We pride ourselves on a track record of transparency and reliability. This means we push for your maximum legal entitlement whilst maintaining rigorous compliance standards. We transform what could be a daunting regulatory procedure into a streamlined opportunity for capital recovery. It's about more than just a tax refund. It's about turning your building's hidden systems into strategic financial assets that support long-term growth.
Why General Accountants Often Miss Integral Features
Standard accounting records rarely tell the whole story of a building's utility. Most bookkeeping is based on historical invoices, which often categorise major refurbishments or acquisitions as a single "land and buildings" figure. Forensic surveying is a distinct discipline. It involves a physical audit to uncover assets that don't appear on a standard invoice, such as background cabling or complex cooling systems. We don't replace your existing accountants; we work alongside them to enhance your tax position. Our specialists provide the detailed technical reports that accountants need to claim the 6% Special Rate allowances accurately without risking HMRC enquiries.
Securing Your Professional Consultation
Starting your journey toward capital recovery is a low-friction process. We've designed our introductory phase to be as simple as possible, requiring only basic property information to provide an initial estimate of your potential relief. There's no aggressive sales pressure. We prefer to demonstrate our value through the quantitative success of our forensic reviews. If you're ready to explore how much capital is currently trapped in your commercial property, speak with a Recoup Capital specialist today. Let's work together to ensure your property's integral features capital allowances are fully utilised to bolster your bottom line.
Ready to Transform Your Property Assets?
Your commercial property is more than just a physical space; it's a strategic financial tool that should be working for you. By correctly identifying integral features capital allowances, you move beyond the surface-level accounting that often misses the hidden value within your electrical and water systems. You've seen how the 6% Special Rate pool and the £1 million Annual Investment Allowance can be balanced to significantly reduce your Corporation Tax liability. It's about ensuring your business isn't overpaying for assets you've already purchased.
We understand that the complexity of the legislation can be intimidating. That's why our team of Chartered Tax Accountants and forensic surveyors acts as your proactive guide through the process. Our success-based fee model ensures there's no upfront risk to your business, whilst our proven track record in the construction and commercial property sectors provides the reliability you need. We're here to help you turn these potential savings into a powerful asset for your company's future growth.
Don't let your tax relief remain trapped in the fabric of your building. You can unlock the hidden value in your property with a specialist Capital Allowances review today. We look forward to helping you innovate and recover the capital your business deserves.
Frequently Asked Questions
What is the current rate for integral features capital allowances in 2026?
The current writing down allowance for the special rate pool, which includes integral features capital allowances, is 6% for the 2026 tax year. Whilst the main pool rate recently decreased to 14%, the special rate remains steady. Additionally, limited companies can benefit from a 50% first-year allowance on new special rate expenditure that exceeds the annual limit.
Can I claim integral features on a property I bought years ago?
You can often make a retrospective claim on a property acquired years ago, provided you still own the assets and they're still in use. Forensic surveyors specialise in identifying these "embedded" allowances that were missed at the point of purchase. There's no strict time limit for claiming on assets you still own; the tax benefit simply applies to your current and future tax periods.
Do solar panels count as an integral feature?
Solar panels are classified as special rate assets, but they aren't technically defined as "integral features" under Section 33A of the legislation. Whilst they sit in the same 6% tax pool, they fall under a different legislative category for plant and machinery. This distinction is minor for most businesses as the tax relief rate and AIA eligibility remain identical to those of integral features.
What happens if I don’t use a Section 198 election when buying a building?
Failing to secure a Section 198 election within two years of a property transfer usually means the tax relief is lost forever. This election fixes the value of the fixtures being transferred between the buyer and the seller. Without it, the "Fixed Value Requirement" isn't met, and neither party can claim on those specific assets in the future.
Are LED lighting upgrades considered integral features?
Yes, LED lighting upgrades are classified as integral features capital allowances. Because lighting systems are explicitly listed in the Capital Allowances Act 2001, the entire cost of the upgrade; including the units and the installation; qualifies for relief. These projects are often ideal candidates for the £1 million Annual Investment Allowance to secure 100% relief immediately.
Can I claim capital allowances on a leased commercial property?
Tenants can absolutely claim capital allowances on leased properties, provided they've incurred the capital expenditure themselves. This typically applies to fit-outs, refurbishments, or the installation of new systems like air conditioning. The key requirement is that the claimant must hold an interest in the land, such as a leasehold, at the time the costs are incurred.
How does the Annual Investment Allowance affect integral features?
The Annual Investment Allowance (AIA) is the most efficient way to claim for these assets because it provides 100% relief in the year of purchase. Since the AIA limit is permanently set at £1 million, most businesses can write off the entire cost of their integral features immediately. This is far more effective than relying on the standard 6% annual writing down allowance.
Is thermal insulation always an integral feature?
Thermal insulation is only considered an integral feature when it's added to an existing commercial building. If the insulation is part of the original construction of a new build, it generally doesn't qualify under these specific rules. However, upgrades to roofs, walls, or floors in existing premises are eligible for the 6% special rate pool as part of a refurbishment.


