

Could a 150% tax deduction be the strategic catalyst that turns a stalled brownfield site into your most profitable venture of 2026? For many UK developers, the unforeseen costs of site preparation often feel like an insurmountable barrier. You’ve likely faced the frustration of complex HMRC definitions whilst trying to manage the significant cash flow strain that comes with cleaning up contaminated land. It’s a common challenge in the industry, but it shouldn’t be a project killer.
In this guide, we’ll show you how to navigate the 2026 land remediation relief landscape to maximise your financial returns and boost project viability. We’ll explain the mechanics of the 150% deduction, show loss-making companies how to secure a 16% cash credit, and clarify exactly what qualifies as derelict land under the latest regulations. You’ll gain a clear roadmap to ensure HMRC compliance whilst transforming remediation expenses into a strategic asset for business growth. We’ve designed this overview to help you master the technical complexities of the current tax year with confidence and precision.
Key Takeaways
- Transform site preparation costs into a strategic asset by applying the 150% super-deduction against your company's taxable profits.
- Identify qualifying land remediation expenditure with precision, ensuring that staff costs, materials, and specialised equipment fuel are all accurately captured.
- Master the forensic tracking and baseline environmental assessment requirements needed to satisfy HMRC and avoid lengthy inquiries.
- Use recovered capital as a funding tool to enhance bid competitiveness and improve the overall viability of marginal brownfield projects.
- Secure essential liquidity for loss-making ventures by surrendering qualifying losses for a 16% payable cash credit.
What is Land Remediation Relief (LRR) and Why Does It Matter?
Land Remediation Relief is a UK tax incentive allowing companies to claim 150% relief on costs incurred in cleaning up contaminated or derelict land. This isn't merely a small tax break; it's a significant fiscal tool designed to breathe life into blighted sites that would otherwise remain unviable. By offering a deduction of up to 150% on qualifying expenditure, the UK government actively incentivises businesses to choose brownfield sites over greenfield expansion. This approach aligns with national targets for urban regeneration and ensures that previously developed land is returned to productive use.
For many businesses, the high costs of Environmental remediation can cripple a project's feasibility before the first brick is laid. This relief acts as a protective buffer, transforming these heavy upfront costs into strategic assets that can be reinvested. Whether you're a developer looking to improve your margins or an investor aiming to increase the value of a portfolio, understanding how to leverage this relief is essential for modern project planning. It turns the financial burden of site preparation into a manageable, and often profitable, part of the development cycle.
Who is Eligible to Claim LRR?
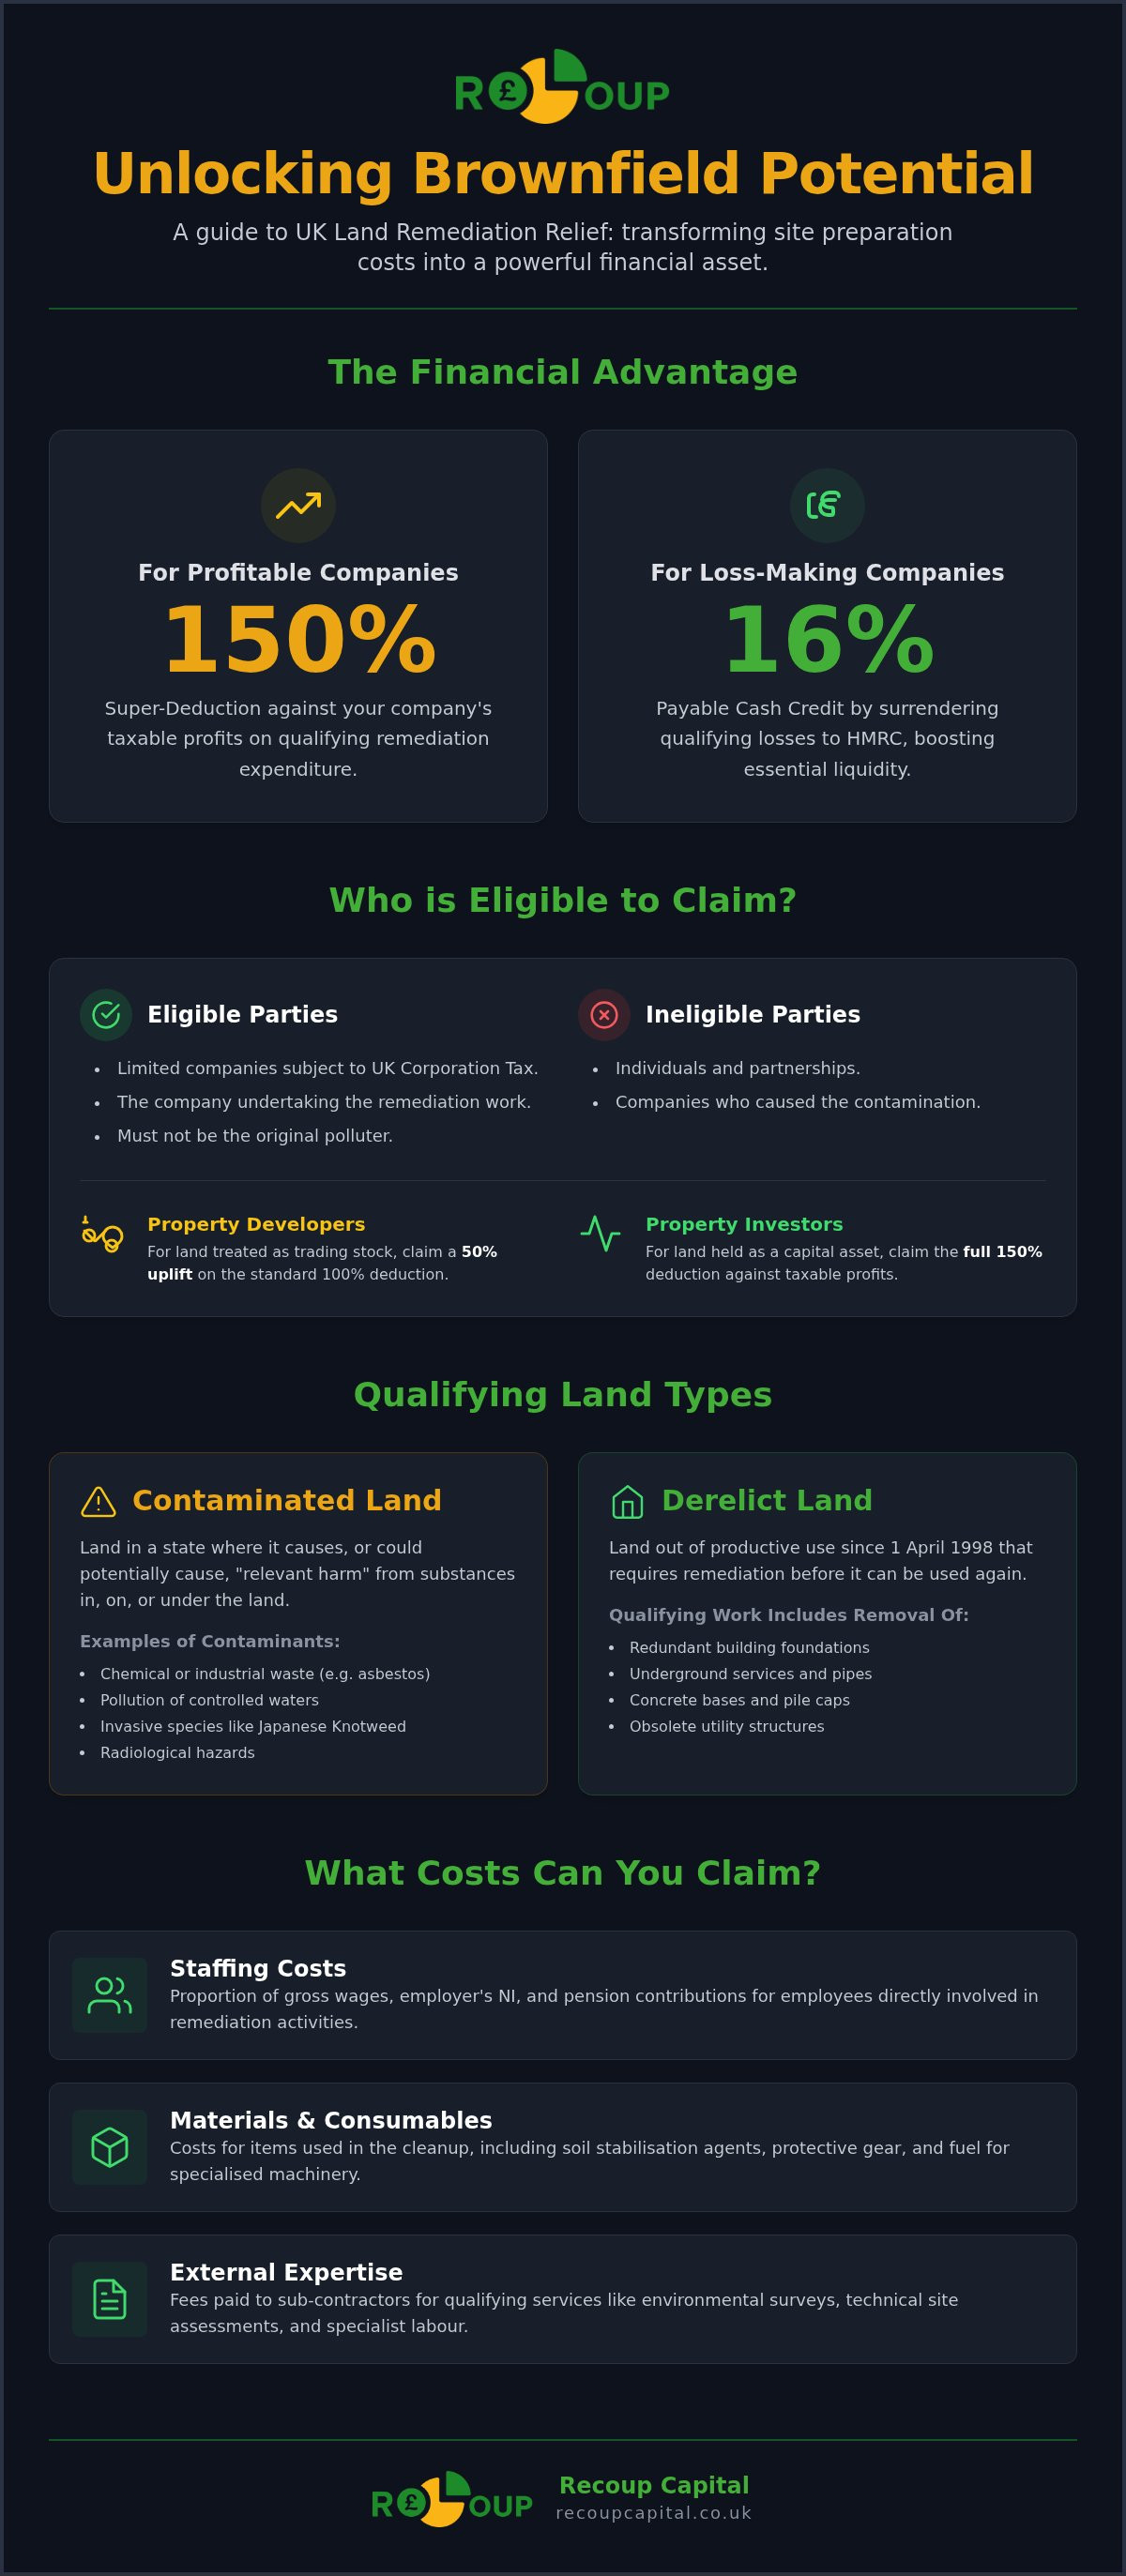
Eligibility for this relief is strictly limited to limited companies subject to UK Corporation Tax. Unfortunately, individuals and partnerships aren't able to access these specific benefits. To secure a successful claim, your company must be the party responsible for the remediation work. Crucially, the "polluter pays" principle is a hard boundary here. You cannot claim if your company, or any connected person, was responsible for the original contamination. The relief is accessible to two primary groups:
- Property Developers: Those who treat the land as trading stock and can claim a 50% uplift on top of their standard 100% deduction.
- Property Investors: Those who hold the land as a capital asset and can claim the full 150% as a deduction against taxable profits.
The Difference Between Contaminated and Derelict Land
Understanding the distinction between contaminated and derelict land is vital for your 2026 tax planning, as the evidence required by HMRC differs for each. Land is considered contaminated if it's in a state where it causes, or could cause, "relevant harm" or significant pollution to controlled waters. This often involves biological, chemical, or radiological hazards that require specialised treatment.
In contrast, derelict land is defined as land that has been continuously out of use since at least 1 April 1998. Qualifying for relief on derelict land usually involves the removal of redundant post-1998 structures, such as old foundations or underground services, to prepare the site for new construction. Identifying which category your project falls into is the first step in building a robust land remediation claim. Misclassifying these can lead to HMRC inquiries, so precision at the assessment stage is your best defence.
Identifying Qualifying Expenditure: What Costs Can You Claim?
Securing the full value of land remediation relief requires a forensic approach to your project's accounts. It's not just about the big-ticket invoices from specialist contractors. Many companies overlook the granular, day-to-day expenses that quickly accumulate during a complex cleanup. To maximise your claim, you must categorise your spending into three primary areas: staffing, materials, and external expertise. Each category carries specific HMRC requirements for documentation and technical justification.
Staff costs often represent a significant portion of a claim. You can include a proportion of the gross wages, employer National Insurance, and pension contributions for employees directly engaged in the remediation process. This might include site managers overseeing the removal of hazardous waste or internal engineers designing the treatment strategy. If your team is also innovating new ways to handle site challenges, you might find additional value elsewhere; learn more about R&D tax credits in construction to see if your technical problem-solving qualifies for further relief.
Materials and consumables are equally vital. This includes everything from the chemicals used for soil stabilisation to the protective gear required for handling asbestos. Even the fuel used by specialised machinery during the remediation phase is a qualifying expense. When working with sub-contractors, ensure their fees for environmental surveys and technical engineering are clearly itemised. These specialists provide the baseline data HMRC expects to see in a robust submission. For a clearer picture of your potential recovery, an expert assessment of your site costs can help identify often-missed expenditure.
Common Contaminants Covered by the Relief
The scope of the relief is broader than many developers realise. Asbestos is a primary driver, whether it's being stripped from an old factory unit or cleared from contaminated topsoil during a refurbishment. Natural contaminants also qualify if they pose a risk of relevant harm. This includes radon, arsenic, and the persistent challenge of Japanese Knotweed, provided you're using active treatment methods rather than simple disposal. Industrial pollutants like heavy metals, oils, and chemical residues from previous site usage are also standard qualifying factors for 2026 claims.
Excluded Costs and Methods
HMRC maintains strict boundaries on what doesn't qualify. The "polluter pays" principle remains the most significant hurdle. If your company, or a connected entity, caused the contamination, you're ineligible for the relief. Standard site clearance, such as removing general fly-tipped rubbish or levelling land for purely aesthetic reasons, is also excluded. Perhaps most importantly, "dig and dump" methods are increasingly scrutinised. HMRC prefers environmentally friendly on-site treatments, and landfill tax incurred during soil disposal is explicitly non-qualifying. Focusing on sustainable, on-site land remediation techniques isn't just better for the planet; it's often more tax-efficient.
Calculating the Value: 150% Deductions and Cash Credits
The actual value of land remediation relief depends on your company's tax position and the nature of your interest in the site. For every £100,000 spent, an investor could see a £37,500 tax saving (at a 25% tax rate). This recovery isn't just a line item on a tax return; it's a strategic injection of capital that can fund the next phase of your development or improve the viability of future acquisitions.
Investors or owner-occupiers benefit from a 150% super-deduction against their taxable profits. This allows you to deduct the actual cost plus an additional 50% uplift from your corporation tax bill. For developers who treat land as trading stock, the mechanics differ slightly. You already deduct 100% of the costs as part of your normal accounting; the relief provides a further 50% uplift, effectively bringing the total deduction to the same 150% level. This ensures that regardless of your business model, the incentive to revitalise blighted land remains equally powerful.
Worked Example: Investor vs. Developer
To illustrate the impact, consider a company that spends £200,000 removing asbestos from a newly acquired warehouse. As an investor holding the site as a capital asset, your taxable profit is reduced by £300,000, creating an immediate and substantial tax saving. A developer, meanwhile, receives a "bonus" £100,000 deduction on top of the cost of sales already recorded in their accounts. These figures demonstrate why land remediation is a vital consideration during the early stages of site appraisal and financial modelling.
The 24% Cash Credit for Loss-Making Companies
For many start-up developers or firms in a growth phase, taxable profits may be non-existent in the early years of a project. In these scenarios, the relief remains accessible through a cash credit option. Loss-making firms can surrender their remediation loss to HMRC in exchange for a 24% cash payment. This provides a critical lifeline, injecting liquidity back into the business whilst the project is still in its capital-intensive phase. It transforms a potential tax loss into a tangible cash asset that supports ongoing operations.
This cash credit is often managed alongside other incentives, such as Capital Allowances for property fixtures. While Capital Allowances focus on the internal plant and machinery, land remediation relief addresses the very ground your project stands on. Combining these strategies ensures you aren't leaving any capital on the table, allowing you to maximise the financial return on every pound spent on site preparation.
How to Submit a Successful Land Remediation Claim
Submitting a successful claim is a multi-stage process that requires technical precision and financial rigour. It isn't enough to simply present a list of costs to HMRC; you must build a compelling case that justifies the relief. The journey begins with a thorough environmental site assessment to establish the baseline contamination before any work commences. This document is your primary evidence, proving that the site met the criteria for relief at the point of acquisition. Without this baseline, evidencing the necessity of the work becomes significantly more difficult during an inquiry.
Once the baseline is set, you must track all qualifying expenditure with forensic detail during the remediation phase. As we explored in previous sections, this includes everything from specialist contractor fees to the fuel used in site machinery. After the physical work is complete, you will need to quantify these costs and integrate the final figures into your CT600 Corporation Tax return. For many businesses, the most effective way to manage this complexity is to partner with a specialist consultant who can manage the entire HMRC liaison process and minimise the risk of a time-consuming inquiry.
The Importance of the Technical Narrative
In 2026, HMRC expects a detailed technical narrative to accompany every land remediation claim. "Just the numbers" will no longer suffice. This narrative must clearly define "relevant harm" in the context of your specific project, explaining exactly how the contamination posed a risk to human health, buildings, or the local ecosystem. You must provide undeniable evidence that the land was in a contaminated state before you intervened. This report bridges the gap between environmental engineering and corporate finance, translating site data into the language of tax compliance. It's the document that protects your claim from being dismissed as standard site clearance.
Deadlines and Retrospective Claims
Many companies are surprised to learn that they can claim for projects already completed. HMRC allows a three-year window for claims, meaning you may still be able to recover costs for remediation work finished in 2024 or 2025. By amending previous tax returns, you can recover overpaid corporation tax and inject that capital back into your current operations. Given the potential for legislative shifts, understanding why you should claim now rather than later is vital for protecting your project's bottom line. Missing these windows often means leaving significant strategic assets on the table. Taking a proactive approach allows you to secure these returns whilst the evidence is still fresh and the regulatory window remains open.
Strategic Reinvestment: Making LRR Work for Your Business
How do you win a competitive bid on a brownfield site without compromising your eventual margins? If you treat land remediation costs as a simple liability, you're likely overestimating the true financial burden of the project. By reframing these costs through the lens of tax recovery, you can transform a "marginal" site into a high-yield opportunity. This shift in perspective allows you to factor potential tax savings into your land acquisition appraisals, giving you the confidence to bid more competitively whilst protecting your bottom line.
Recovered capital shouldn't just sit in a bank account. It's a strategic asset designed for reinvestment. Whether you're upgrading specialised machinery or funding new R&D initiatives, the liquidity provided by land remediation relief acts as a non-dilutive funding stream. At Recoup Capital, we don't just process paperwork; we act as a protective guide through the complexities of the regulatory landscape. Our partnership-led approach ensures that your financial returns are maximised, allowing you to focus on innovation and growth rather than the intricacies of HMRC compliance.
Integrating LRR into Development Appraisals
The impact of tax relief on a project’s Internal Rate of Return (IRR) can be transformative. When you factor in a 150% deduction or a 24% cash credit during the early planning stages, the viability of a heavily contaminated site changes significantly. This foresight allows you to accurately model cash flow and potentially secure better financing terms. If you're looking to refine your project's financial structure, you might explore our Corporate Finance advisory services to see how we align tax recovery with your broader business goals. This proactive planning turns technical challenges into quantitative success metrics.
Why Specialist Advice Outperforms General Accounting
General bookkeeping is essential for day-to-day operations, but forensic tax surveying is a different discipline entirely. A general accountant may understand the broad strokes of corporation tax, but they often lack the specialised engineering insight required to justify "relevant harm" to HMRC. Our team of experts provides the technical depth needed to manage complex claims that often involve overlapping areas like Stamp Duty Land Tax and Capital Allowances. We ensure that every qualifying pound is captured whilst maintaining absolute compliance.
Our success-based fee model ensures our interests are perfectly aligned with yours. There are no upfront costs; we only succeed when you do. This results-driven philosophy provides the peace of mind that your claim is being handled by specialists who are personally invested in the outcome. It’s a long-term collaboration built on transparency and reliability, designed to turn regulatory hurdles into approachable opportunities for your business.
Unlock the Strategic Value of Your Brownfield Sites
Success in 2026 requires viewing site preparation through a lens of capital recovery rather than just expense. By leveraging the 150% deduction or the 24% cash credit, you transform the financial burden of land remediation into a strategic business tool. Technical precision and forensic documentation are your best defences against HMRC inquiries, ensuring that every qualifying pound is captured and protected.
Our specialist chartered tax accountants bring deep construction sector expertise and national UK coverage to every project. Because we operate on a success-based fee model, we only win when you do; this ensures our interests are perfectly aligned with your project's profitability. We act as your protective guide, handling the regulatory complexities so you can focus on building the future. Discover how much your land remediation claim is worth with a no-cost consultation and see how our results-driven approach can benefit your next development. Your path to capital recovery starts with a single conversation.
Frequently Asked Questions
Can I claim Land Remediation Relief if I bought the land already contaminated?
Yes, you can claim the relief if you acquired the site in a contaminated state. The primary condition is that your company, or any person connected to you, wasn't responsible for causing the original pollution. Land remediation relief is designed specifically to encourage the purchase and revitalisation of blighted sites. Whether you're dealing with industrial chemical residues or historical ground pollutants, you can claim the 150% deduction on the costs required to make the site safe.
Is Japanese Knotweed removal always eligible for tax relief?
No, eligibility depends on the treatment method used and the impact on the development. HMRC typically excludes "dig and dump" disposal where the weed is simply moved to a landfill. To qualify for the 150% relief, you should use active, sustainable treatment methods such as on-site chemical application or biological control. The infestation must also pose a risk of relevant harm to your planned structures or the wider environment to meet the necessary criteria.
How does Land Remediation Relief interact with R&D Tax Credits?
They're separate incentives that often apply to the same project. While LRR covers the physical costs of cleaning the site, R&D tax credits apply if your team develops new, innovative technical solutions to solve unique contamination challenges. If your project involves technical uncertainty that requires bespoke engineering, you could potentially claim both. It's essential to correctly apportion your expenditure between physical remediation and technical innovation to ensure you maximise your total return whilst remaining compliant.
Can a loss-making company receive a cash payment for land remediation?
Yes, loss-making companies can surrender their qualifying losses for a 16% payable cash credit. This provides essential liquidity during the capital-heavy phases of a development project. By surrendering the land remediation loss, you turn a potential future tax benefit into immediate capital. This is particularly useful for start-ups or firms in a growth phase that haven't yet generated taxable profits but need to maintain a steady cash flow for ongoing site works.
What is the time limit for making a retrospective LRR claim?
The standard window for making a claim is three years from the end of the accounting period in which the expenditure was incurred. This means you can often amend previous corporation tax returns to recover costs for projects completed in 2024 or 2025. It's a valuable opportunity to reclaim overpaid tax and inject that capital back into your current operations. However, you should act quickly, as missing these statutory deadlines means losing the chance to recover these strategic assets.
Is asbestos removal from an existing building eligible for LRR?
Yes, asbestos removal is one of the most common drivers for successful claims. If you've acquired a building for refurbishment or demolition and it contains asbestos, the costs of safe removal and disposal are qualifying expenses. This includes the fees for specialist contractors, protective equipment, and the necessary environmental surveys. Providing the building was acquired for your company's trade or investment, these costs can be treated as part of the 150% super-deduction against your profits.
Do I need a specialist surveyor to claim Land Remediation Relief?
While not a legal requirement, using a specialist is highly recommended to protect your claim. HMRC requires a detailed technical narrative and forensic evidence of the baseline contamination. A specialist consultant ensures that "relevant harm" is correctly defined and that all qualifying costs, including staff time and materials, are captured accurately. This professional oversight significantly reduces the risk of an inquiry and ensures you don't leave any capital on the table through missed expenditure.
Can I claim LRR on land I intend to hold as a long-term investment?
Yes, the relief is available to property investors as well as developers. If you hold land as a capital asset for long-term growth or rental income, you can claim the full 150% deduction against your taxable profits. This improves the internal rate of return on your investment by significantly reducing the net cost of site preparation. It transforms the necessary burden of cleaning up a blighted site into a strategic asset that enhances your portfolio's overall value.


