

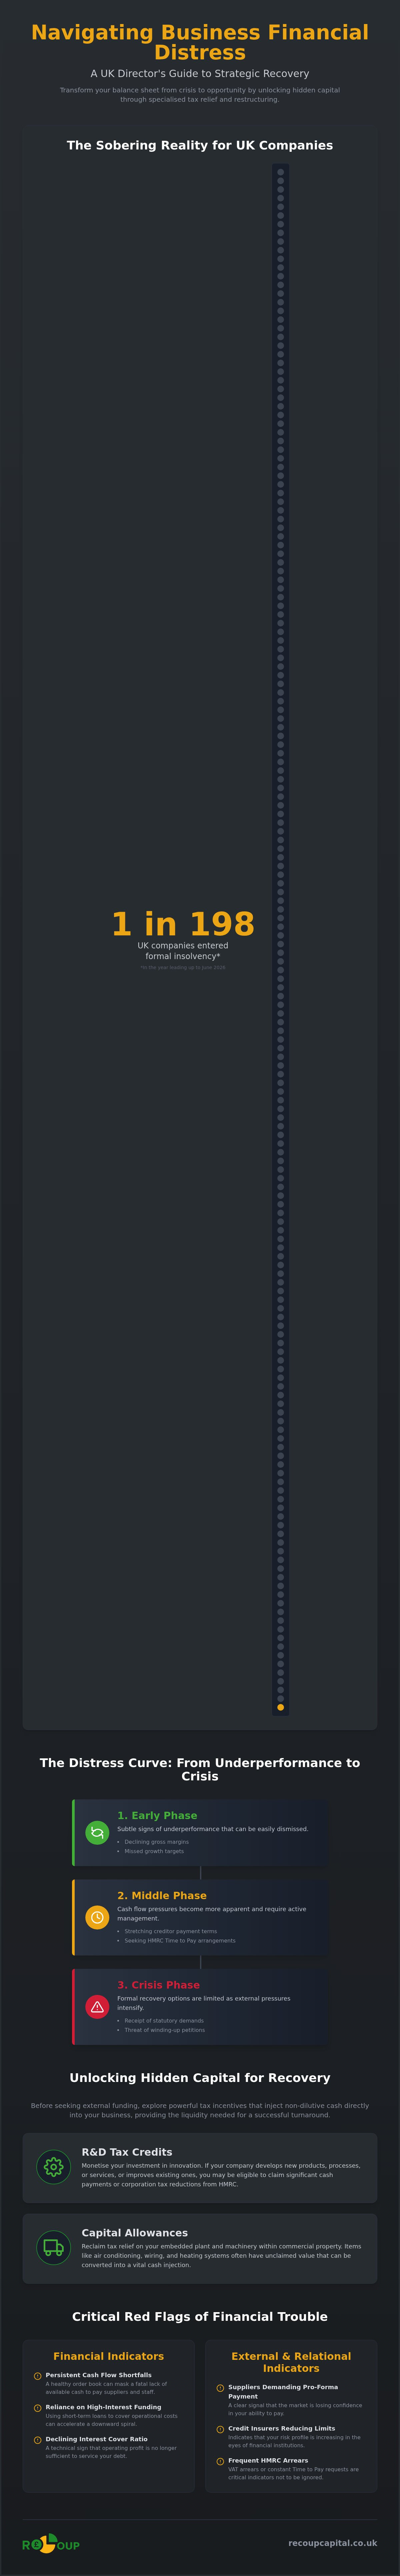
Did you know that in the year leading up to June 2026, one in every 198 UK companies entered formal insolvency? It's a sobering figure that highlights the intense pressure many directors currently face from HMRC and persistent creditors. You're likely feeling the weight of mounting debt and the frustration of restricted liquidity, whilst wondering if formal administration is your only remaining path.
This guide reveals a different trajectory, showing how business recovery tax relief uk and strategic restructuring can transform your balance sheet. We don't believe in traditional sales pitches; instead, we focus on demonstrating how to unlock hidden capital reserves through specialised incentives like R&D tax credits and capital allowances. By the end of this article, you'll understand the mechanics of corporate finance advisory and forensic tax recovery. These tools are designed to help you reduce debt burdens, inject vital cash, and return your enterprise to profitable growth. We will explore how to navigate the complexities of the current regulatory landscape to turn your financial challenges into a strategic opportunity for innovation.
Key Takeaways
- Learn to distinguish between temporary cash flow hiccups and systemic insolvency to determine the most effective path for your company's survival.
- Evaluate the strategic benefits of informal creditor negotiations versus formal Company Voluntary Arrangements (CVAs) to manage debt and protect your operations.
- Discover how to inject non-dilutive cash into your firm by leveraging business recovery tax relief uk through R&D tax credits and capital allowances.
- Implement a robust 13-week stabilisation plan that prioritises essential payments whilst uncovering hidden capital reserves for future growth.
- Understand how a success-based fee model allows distressed businesses to access expert corporate finance advisory without the burden of upfront costs.
Understanding Business Financial Distress in the UK Market
Financial distress occurs when a business can no longer meet its financial obligations as they fall due. It's vital to distinguish between a temporary cash flow hiccup, perhaps caused by a late payment from a major client, and systemic insolvency. The latter suggests a deeper, structural failure where liabilities outweigh assets. In the 2026 economic environment, where the Corporation Tax main rate is 25% for profits over £250,000 and the small profits rate is 19%, maintaining a proactive stance on liquidity is essential. This period is known as the Recovery Window. It's the most effective time to explore business recovery tax relief uk before the situation escalates. Understanding the nuances of UK insolvency law can help directors identify when their duties shift from shareholders to creditors. Acting during this window allows for restructuring that preserves value rather than simply managing a decline.
The Distress Curve: From Underperformance to Crisis
The journey toward insolvency is rarely a sudden event. It usually begins with subtle underperformance that directors often dismiss as seasonal variations. Recognising where you sit on the curve is vital for survival:
- Early Phase: Declining gross margins and missed growth targets.
- Middle Phase: Stretching creditor terms and seeking HMRC Time to Pay arrangements.
- Crisis Phase: Receipt of statutory demands and the threat of winding-up petitions.
Directors might find themselves spending more time managing debt than driving sales. Without intervention, the crisis phase leaves very little room for strategic manoeuvring or capital recovery. Identifying these markers early is the first step toward a successful turnaround.
Why Traditional Accounting Often Misses Warning Signs
Many directors rely on year-end accounts to gauge health, but these are retrospective by nature. In a fast-moving crisis, looking at last year's performance is like driving a car while looking in the rearview mirror. A business can report a healthy paper profit whilst simultaneously running out of available cash to pay staff or suppliers. This discrepancy is why real-time management information is a cornerstone of corporate finance strategies. Accurate, up-to-the-minute data allows for the identification of unoptimised capital that could be reclaimed through business recovery tax relief uk. This provides the immediate liquidity needed to pivot back to stability before the crisis becomes terminal.
Identifying the Critical Indicators of Corporate Financial Trouble
Steady sales volume can often mask a deteriorating balance sheet. It's a common misconception that a busy order book equals a healthy business. When cash flow shortfalls persist despite consistent revenue, it usually indicates that your working capital is trapped or your margins are being eroded by rising costs. Directors should consult the official guidance on corporate financial distress to understand how these early signals manifest. An increasing reliance on short-term, high-interest funding is another red flag. Whilst these loans provide immediate relief, the debt service costs often accelerate the downward spiral. A declining interest cover ratio is a technical indicator that your operating profit is no longer sufficient to meet your interest obligations.
External relationships often signal trouble before internal reports do. If key suppliers are demanding pro-forma payments or credit insurers are reducing your limits, it's a sign the market is losing confidence. Frequent Time to Pay requests or VAT arrears with HMRC are critical indicators that shouldn't be ignored. These issues often lead to internal friction amongst the board as directors disagree on which creditors to prioritise. This emotional strain can cloud judgment at the very moment clarity is needed. Identifying these stresses early allows you to explore specialised corporate finance advisory to restructure debt before it becomes unmanageable. It's often the first step in qualifying for business recovery tax relief uk by demonstrating a commitment to a viable turnaround.
Operational vs Financial Red Flags
Operational issues often precede financial collapse. High staff turnover, declining product quality, and supply chain delays suggest a loss of control that eventually hits the bottom line. These red flags then trigger financial breaches, such as failing bank covenants or a sharp increase in debtor days. This creates a dangerous feedback loop. As operations falter, liquidity dries up; as liquidity dries up, operations falter further. Breaking this cycle requires a dual approach that addresses both the operational inefficiencies and the underlying capital structure.
The Role of HMRC Compliance in 2026
HMRC has adopted a significantly stricter stance on transparency in 2026, particularly regarding the merged R&D tax credit scheme. An unexpected HMRC inquiry can be the tipping point for a business already in distress. It's no longer enough to simply submit a claim. You need forensic-level accuracy to ensure your filings act as a lifeline rather than a liability. Accessing business recovery tax relief uk requires a meticulous approach to compliance. By ensuring all claims are robust and fully evidenced, you can unlock vital capital without inviting unnecessary regulatory scrutiny. This precision is essential for maintaining the trust of both the tax office and potential recovery partners.
Formal vs Informal Restructuring: Which is Right?
Once you've identified the critical indicators of trouble, the focus must shift from observation to active intervention. The first instinct for many directors is to enter direct negotiations with banks and major creditors. This informal restructuring involves revising payment schedules or requesting interest holidays to buy valuable time. It's often the fastest route to stabilisation and maintains a higher degree of confidentiality. However, if creditors are becoming aggressive, formal legal protection becomes a necessity. A Company Voluntary Arrangement (CVA) allows a limited company to pay back a proportion of its debts over a fixed period whilst continuing to trade. It requires the consent of 75% of voting creditors but provides a structured, legally binding path back to health. This legal framework often works in tandem with business recovery tax relief uk, as recovered capital can be used to fund the agreed CVA payments.
Administration offers a different type of shield. It provides a legal moratorium that prevents creditors from taking action, giving the business breathing space to restructure or find a suitable buyer. Debt restructuring is another powerful lever available to directors. By swapping debt for equity or extending loan terms, you can significantly reduce monthly cash outflows and improve your debt-to-equity ratio. These strategies aren't signs of failure. They're tactical manoeuvres used by resilient boards to ensure long-term viability and protect the interests of stakeholders.
Choosing between formal and informal paths depends on your specific pressure points and the level of creditor cooperation. Informal work-outs are discrete and cost-effective, helping to preserve your company's credit rating and public reputation. They lack legal teeth, however, meaning a single dissenting creditor can derail the entire process. Formal routes like CVAs or administrations offer robust legal protection but appear on public records. This visibility can impact your future credit rating for several years, yet the trade-off is a guaranteed stop to winding-up petitions and statutory demands. Deciding which route to take requires a clear-eyed assessment of your creditor landscape.
Corporate Finance as a Strategic Pivot
Stabilisation is only the first phase of a successful turnaround. To truly recover, you must pivot toward growth and sustainable liquidity. This is where corporate finance becomes a strategic asset. Securing new investment often hinges on a professional valuation that looks beyond current distress to identify the underlying value of your intellectual property or market position. Presenting a compelling turnaround case to lenders requires demonstrating how you will use business recovery tax relief uk to bridge liquidity gaps. By showing a clear path from debt management to capital injection, you transform your business from a high-risk entity into a high-potential opportunity for future investors.
Unlocking Internal Capital: R&D Tax Credits and Capital Allowances
Most recovery strategies focus on cutting costs or borrowing. This approach often overlooks a significant source of non-dilutive liquidity: the tax office. For many UK firms, business recovery tax relief uk represents an untapped reservoir of capital that can be injected directly into operations without surrendering equity or increasing debt. By identifying qualifying expenditure in innovation and property, you can transform past costs into future growth. We operate on a success-based fee model to ensure this opportunity remains accessible. This structure removes the barrier of upfront costs, which is particularly vital for firms currently managing tight cash flow constraints. Our goal is to demonstrate value through tangible results before any fee is even discussed.
Beyond innovation, your physical assets often hold hidden value. Capital Allowances allow you to write off the cost of qualifying capital assets against your taxable profits. This isn't just about machinery. It includes "integral features" within commercial buildings such as air conditioning, electrical systems, and lifts. For construction or property development firms, Land Remediation Relief offers a 150% tax deduction for qualifying costs spent on cleaning up contaminated or derelict land. These incentives provide a much-needed cash injection precisely when traditional lending might be restricted. If you're ready to see how these reliefs apply to your specific situation, discover why claiming now is a critical step for your recovery.
The R&D Lifeline for Innovation-Led Firms
Many companies in distress stop claiming tax incentives exactly when they need them most, often due to the mistaken belief that they are too busy to process the paperwork. This is a missed opportunity. As R&D tax credits explained in our detailed guide show, these credits are a vital cash lifeline. A common misconception is that you need to be profitable to claim. In reality, the Enhanced R&D Intensive Support (ERIS) scheme allows loss-making SMEs to receive a payable tax credit of up to 14.5% of their surrenderable loss. This provides an immediate cash boost to help sustain your R&D teams whilst you restructure.
Forensic Tax Analysis: Finding Hidden Cash
General accountants often lack the specialised surveying skills required to identify every qualifying embedded fixture in a commercial property. Forensic tax analysis goes deeper, using chartered accountants and surveyors to uncover savings that frequently go unnoticed in standard filings. Capital Allowances function as a legitimate tax-deductible fixture recovery that offsets the cost of commercial property improvements against your taxable profits. By conducting a forensic review, we can often identify thousands of pounds in unclaimed allowances from previous years. This retrospective recovery can be the difference between a failed turnaround and a successful return to profitability.
Navigating Recovery: A Step-by-Step Stabilisation Plan
Stabilising a business in distress requires a disciplined timeline that moves from immediate survival to long-term resilience. The first 48 hours should focus on gaining absolute visibility. Implementing a 13-week cash flow forecast is the industry standard for this phase. This tool allows you to predict the exact moment cash reserves might dip, enabling you to prioritise essential payments such as payroll and critical suppliers. By categorising creditors based on their impact on continued operations, you can manage outflows without triggering a total shutdown. Transparency with HMRC is paramount during this period. Proactively discussing arrears or Time to Pay arrangements prevents the sudden escalation of enforcement action whilst you prepare your recovery strategy.
Once the immediate bleeding is staunched, the medium-term focus shifts to capital injection. This is the stage where you implement a robust business recovery tax relief uk strategy. By forensically identifying unclaimed R&D credits and capital allowances, you can unlock internal liquidity to fund your restructuring costs. This capital acts as a bridge, reducing your reliance on expensive emergency debt. In the long term, your goal is to refocus the organisation on its high-margin core activities. This often involves divesting from underperforming divisions or renegotiating debt terms to ensure your capital structure supports growth rather than hindering it. Success in 2026 belongs to those who view recovery not as a single event, but as a phased transition back to profitability.
Communicating with Stakeholders Whilst in Distress
Maintaining trust is your most valuable currency during a turnaround. Creditors are far more likely to support a restructuring plan if they receive a clear, evidence-based narrative rather than silence. For employees, the uncertainty of financial trouble can be toxic. Keeping your team motivated requires honest communication about the changes ahead and the path to stability. Shareholders also need careful management, particularly if a debt-for-equity swap is on the table. By presenting these measures as necessary steps to protect the underlying value of their investment, you can align all parties behind the survival of the firm.
Why Partnering with a Specialist Matters
A generalist accountant is excellent for compliance and standard filings, but they often lack the forensic depth required for complex capital recovery. Specialist consultancies bring a dual focus on corporate finance and technical tax law, ensuring every possible relief is maximised. Our success-based model is designed specifically for this scenario. It aligns our interests entirely with your business’s survival; we only succeed when you unlock the capital needed to recover. This partnership-oriented approach removes the financial risk of seeking expert help during a crisis. If you are ready to explore how these strategic assets can protect your company's future, speak to our specialists about your recovery options.
Securing Your Business Legacy Through Strategic Recovery
Returning to profitable growth requires a fundamental shift in how you view your balance sheet. Instead of seeing financial distress as an inevitable decline, treat it as a catalyst for forensic capital optimisation. We've discussed how a structured 13-week plan and proactive stakeholder communication can stabilise your operations. However, the true engine of a turnaround is often found in business recovery tax relief uk. By unlocking non-dilutive cash through R&D credits and capital allowances, you can fund your recovery without surrendering control of your firm.
Recoup Capital has recovered over £100m for clients in the construction, engineering, and tech sectors. Our success-based fee model ensures that expert consultancy is accessible even when liquidity is tight; we only succeed when you do. This partnership-oriented approach is designed to transform intimidating regulatory procedures into genuine opportunities for innovation. You don't have to face HMRC or your creditors without a protective guide by your side.
Take the first step toward reclaiming your company's future. Book a confidential, no-obligation consultation with Recoup Capital today to review your recovery options. It's time to stop managing a crisis and start building for the long term.
Frequently Asked Questions
What is the definition of business financial distress in the UK?
Business financial distress is a condition where a company is unable to meet its financial obligations as they fall due. It often manifests as a lack of liquidity to pay staff, suppliers, or HMRC on time. Whilst it's a precursor to insolvency, it doesn't necessarily mean the business is terminal. Proactive management during this phase is essential for qualifying for business recovery tax relief uk and implementing a successful turnaround.
Can I claim R&D tax credits if my company is making a loss?
Yes, you can claim R&D tax credits even if your company is currently making a loss. Under the 2026 Enhanced R&D Intensive Support (ERIS) scheme, loss-making SMEs with high R&D intensity can receive a payable tax credit of up to 14.5% of their surrenderable loss. This provides a vital non-dilutive cash injection that can support your operations during a period of financial restructuring and recovery.
What is the difference between insolvency and financial distress?
Financial distress describes a period of severe cash flow difficulty, whereas insolvency is a specific legal state. A company is technically insolvent if it fails the "cash flow test" by being unable to pay debts when due, or the "balance sheet test" where liabilities exceed assets. Distress is often the warning phase that precedes formal insolvency. Recognising this early allows directors to seek professional advice and protect their legal position.
How much does a corporate restructuring cost for a UK SME?
The cost of corporate restructuring varies significantly based on the complexity of your debt and the chosen recovery path. Informal negotiations with creditors may involve lower professional fees, whilst formal processes like a CVA involve regulated insolvency practitioner costs. We focus on providing specialised financial consultancy on a success-based fee model. This approach ensures that distressed businesses can access expert capital recovery services without the burden of upfront expenditure.
Can HMRC shut down my business if I have a Time to Pay arrangement?
HMRC generally won't shut down your business as long as you strictly adhere to the terms of a Time to Pay (TTP) arrangement. A TTP acts as a formal agreement to settle tax arrears over a set period, preventing further enforcement action like winding-up petitions. However, if you miss a payment or fail to stay current with new tax liabilities, HMRC can cancel the arrangement and resume legal proceedings immediately.
How long does a Company Voluntary Arrangement (CVA) last?
A Company Voluntary Arrangement (CVA) typically lasts between three and five years. During this period, the company makes regular, agreed payments to a supervisor, who then distributes the funds to creditors. If the business successfully completes the term, any remaining unsecured debt included in the arrangement is legally written off. This structured timeline provides a clear path for the company to return to a stable, debt-free position in the long term.
What are Capital Allowances and how do they help with cash flow?
Capital Allowances are a form of tax relief that lets you deduct the cost of qualifying capital assets from your taxable profits. This includes machinery, vehicles, and "integral features" like electrical systems in commercial buildings. By claiming these, you reduce your Corporation Tax bill or potentially trigger a tax refund. This process is a cornerstone of business recovery tax relief uk, helping to unlock trapped capital within your property assets.
Is my business eligible for Land Remediation Relief?
Your business is likely eligible for Land Remediation Relief if you are a UK company carrying out a trade that involves cleaning up contaminated or derelict land. This relief offers a 150% tax deduction for qualifying expenditure, such as removing asbestos or treating chemical pollutants. It's particularly valuable for construction and property firms in distress, as it significantly lowers the tax burden associated with complex and expensive development projects.


